
Blogs
EVP Market at 7.2% CAGR: Why the $300M Shift to 2032 Changes EV Strategy
By pmarketresearch, 2026-09-21
The Strategic Evolution of the Automotive Electric Vacuum Pump Market: Trends and Commercial Opportunities
The automotive electric vacuum pump (EVP) market is undergoing a structural transformation driven by electrification, tightening emissions mandates, and the growing complexity of brake and engine management architectures. As automakers transition from mechanically dependent vacuum sources to electrically actuated systems, the EVP has evolved from a peripheral auxiliary component into a critical node in vehicle safety, efficiency, and emissions compliance. The segment has expanded from approximately $116 million in 2020 to an estimated $186 million in 2025, with forward projections indicating a compound annual growth rate of 7.2 percent through 2032. This trajectory reflects more than steady demand growth; it signals a recalibration of how vehicles generate, manage, and deploy vacuum across braking, emission, and engine control functions.
For executives, investors, and procurement leaders, understanding the EVP market requires looking beyond unit sales and pricing. The segment is shaped by regulatory pressure, platform electrification strategies, supplier differentiation in adaptive control and power efficiency, and cost structures that still challenge widespread adoption. The following analysis examines the market environment, the forces shaping demand, the competitive landscape, and the strategic moves that will define the next three-to-five-year horizon.
Vacuum Pumps Market
Market Landscape and Core Challenges
The EVP market has grown consistently across the 2020 to 2025 period, reflecting steady integration into passenger and commercial vehicle architectures. The growth curve is not uniform, however. It is modulated by regional vehicle mix, electrification adoption rates, and the pace at which legacy vacuum-generating systems are replaced by electric alternatives. Asia Pacific currently represents the largest revenue pool, followed by Europe and North America, with Latin America and the Middle East/Africa contributing smaller but expanding shares. This geographic distribution mirrors broader automotive production and sales patterns, while also highlighting where regulatory pressure and electrification investment are most concentrated.
Segmentation by type reveals a market still anchored by diaphragm-type pumps, which dominate due to their mature design, reliability, and compatibility with hybrid and internal combustion platforms. Swing piston and leaf-type designs occupy meaningful but smaller positioning, often differentiated by specific efficiency, packaging, or durability requirements. Application-wise, brake booster systems remain the primary demand center, as electric vacuum generation is essential for reliable braking assist when engine-driven vacuum is unavailable or insufficient. Emission control systems and engine management systems represent secondary but strategically important application areas, where EVPs support precise vacuum-dependent processes and help reduce parasitic mechanical losses.
Three core challenges define the market’s current inflection point:
- Cost barriers and material constraints. The upfront cost of electric vacuum pumps remains a restraint, driven by raw material costs, precision manufacturing requirements, and the need for integrated control electronics. While economies of scale and design optimization are gradually easing this pressure, cost sensitivity continues to influence procurement decisions, particularly in price-competitive segments and emerging markets.
- Regulatory-driven integration complexity. New emissions and fuel economy standards are pushing EVPs from optional auxiliaries into baseline design requirements. This shift forces suppliers and OEMs to reconcile performance, packaging, thermal management, and system integration at earlier design stages, raising the stakes for supplier readiness and development lead times.
- Platform fragmentation across powertrains. The market must simultaneously serve traditional ICE applications, hybrid architectures, and increasingly electrified platforms. Each powertrain path demands different vacuum profiles, control strategies, and reliability expectations. Suppliers that can deliver adaptable EVP families with consistent performance across these environments are better positioned than those optimized for a single use case.
These challenges are not simply headwinds; they are shaping the criteria by which buyers evaluate suppliers and by which companies allocate R&D resources. The market is moving toward solutions that combine reliability, efficiency, and intelligent on-demand operation, rather than standalone vacuum generation.
Key Demand Drivers
Technology Innovation and Adaptive Control
A central driver of EVP adoption is the shift toward adaptive vacuum control and intelligent operation. Pumps are no longer expected to run continuously; instead, they are increasingly designed to respond to real-time braking demand, engine state, and hybrid/electric mode transitions. This reduces parasitic power consumption, improves brake response, and supports fuel efficiency and emissions targets. Recent product launches illustrate this direction clearly. In May 2025, Bosch introduced a new generation of electric vacuum pumps for hybrid and electric vehicles aimed at enhancing braking performance. Continental unveiled a high-performance EVP for passenger ICE platforms in Europe, emphasizing adaptive vacuum control, power efficiency, and integration with regenerative braking. Rheinmetall’s Pierburg division launched an electric vacuum pump focused on reducing CO2 emissions and enhancing hybrid and brake system performance, highlighting rapid vacuum buildup and intelligent on-demand operation. Denso also introduced a diaphragm-type EVP in the Asia-Pacific region for hybrid and ICE engines, with adaptive control intended to improve braking and fuel efficiency.
These developments point to a broader technological trend: the EVP is becoming part of a controlled, responsive system rather than a fixed-output component. Suppliers that integrate adaptive control algorithms, optimize power draw, and coordinate with brake and powertrain controllers are creating differentiation that goes beyond mechanical design. This matters for OEMs because it allows vacuum management to align with broader vehicle efficiency strategies and electrified brake architectures.
Regulatory and Emissions Mandates
Regulatory pressure is one of the most decisive forces in the EVP market. The European Union’s Euro 7 standards, taking effect in 2026, set fleet average CO2 emissions limits of approximately 49.5 g/km for passenger cars, compelling designs that eliminate parasitic mechanical losses and ensure reliable braking with lower emissions. Similar dynamics are visible in China’s National VI emissions standard and California’s Advanced Clean Cars II regulation, which encourage improved fuel efficiency through auxiliary vacuum system implementation across vehicle portfolios. At a broader level, stringent emission and fuel economy regulations are mandating electric vacuum pump integration to maintain braking reliability and reduce emissions in hybrid and electric vehicles.
These regulations affect the market in two ways. First, they expand the addressable base by making EVP integration a compliance consideration for a wider range of vehicle programs. Second, they raise the technical bar, since compliance often depends on system-level performance rather than pump-level specifications alone. Tier-1 suppliers including Robert Bosch, Denso, and Valeo are scaling compliant EVP solutions in response, reflecting the way regulation is shaping supplier roadmaps and production capacity planning. The implication for decision-makers is that EVP demand is not purely cyclical; it is structurally supported by regulatory timelines that are difficult to defer.
Demand-Side Shifts in Vehicle Architectures and Safety Expectations
On the demand side, vehicle architectures are shifting in ways that increase reliance on electric vacuum generation. As engine-driven vacuum sources become less available or less reliable in hybrid and electric contexts, EVPs provide a controllable alternative for brake boosting, emission system operation, and engine management functions. At the same time, consumer and commercial expectations around braking performance, safety, and efficiency are rising. Brake booster systems remain the dominant application because vacuum assist continues to be central to reliable braking feel and response, especially during transitions between powertrain modes.
This demand shift is not limited to passenger cars. Commercial vehicles and xEV braking systems are also creating additional application space for EVPs, particularly where consistent vacuum delivery and system compatibility are required across OEM and aftermarket use. Suppliers that can deliver consistent vacuum performance across passenger and commercial platforms are building broader portfolios that reduce program risk for buyers. The commercial side of the market often places different weight on durability and cost, so balancing performance with value is a strategic priority.
Supply Chain and Cost Structure Dynamics
The supply side of the EVP market is being shaped by material costs, manufacturing complexity, and the need for tighter integration with electronic control systems. High initial costs remain a restraint, but the same factors are encouraging design consolidation, higher production volumes in key regions, and closer collaboration between pump manufacturers and system integrators. This creates a dual dynamic: cost pressure limits rapid adoption in price-sensitive programs, while scale and integration opportunities reward suppliers that can deliver complete, validated solutions rather than stand-alone pump units.
Regional supply chains are also relevant. South Korean suppliers such as Youngshin Precision and LPR Global illustrate the growing role of cost-effective EVP series for passenger vehicles and the strategic importance of suppliers serving EV, hybrid, and high-performance applications. LPR Global, for example, has positioned itself as a primary supplier for EV and hybrid vacuum pump needs, serving a substantial share of South Korean EV makers and providing components for Kia/Hyundai applications through Valeo. Meanwhile, Advik Hi-Tech’s collaboration with Entecnia S.L.U. shows how cross-border partnerships are being used to develop advanced EVP solutions for passenger cars, commercial vehicles, and xEV braking systems. These supply-side patterns indicate that the market is not solely concentrated in traditional European hubs; regional specialists are expanding capabilities and integrating into global OEM and tier-1 networks.
Automotive Vacuum Pump Market
Competitive Landscape and Leading Strategies
The EVP market remains highly concentrated, with a small group of suppliers accounting for the majority of revenue. This concentration reflects the technical barriers to entry, the importance of validation and system integration, and the long development cycles associated with automotive component qualification. At the same time, the competitive field is not static. Incumbents are expanding their EVP portfolios to address hybrid and electric platforms, while regional specialists are gaining traction through cost efficiency, targeted applications, and partnership-based development.
Bosch continues to occupy a leading position as a manufacturer of modular EVPs for automotive brake boosters, with recent expansion into adaptive control for hybrid and electric vehicles and integration with electronic brake systems. Its strategic advantage lies in scale, system-level integration capability, and the ability to align pump development with broader braking and powertrain strategies. Continental competes on high-performance EVP solutions for passenger ICE vehicles, differentiating through adaptive vacuum control, power efficiency enhancements, and regenerative braking integration. Rheinmetall’s Pierburg division emphasizes single- and dual-stage EVPs optimized for hybrid and brake systems, with a focus on low CO2 emissions, rapid vacuum buildup, and intelligent on-demand operation. Hella develops and supplies EVPs specifically for brake booster applications, prioritizing reliable pneumatic brake boost operation in modern vehicles. These European incumbents share a common strategic theme: they are moving beyond component supply toward system-relevant performance, control, and compliance.
In parallel, regional players are carving out differentiated roles. Youngshin Precision produces cost-effective EVP series for passenger vehicles, delivering consistent vacuum delivery for both OEM and aftermarket applications. LPR Global serves as a primary supplier for EV, hybrid, and high-performance vehicles, with a strong footprint among South Korean EV makers and a role in Kia/Hyundai applications through Valeo. Advik Hi-Tech is advancing EVP production in collaboration with Entecnia S.L.U., targeting passenger cars, commercial vehicles, and xEV braking systems. Valeo functions as a recipient and integrator of EVP components, including SMVP series parts for installation in Kia and Hyundai advanced automobiles. Denso supplies diaphragm-type EVPs for hybrid and ICE engines, emphasizing adaptive vacuum control and fuel efficiency improvements. This mix of large incumbents and specialized suppliers creates a landscape where technical leadership, cost positioning, and regional supply relationships all matter.
Recent developments reinforce the pace of competitive activity. In early 2025, Advik Hi-Tech showcased a new range of automotive components at the Bharat Mobility Global Expo in New Delhi, including advanced EVPs developed with Entecnia S.L.U. for passenger and commercial braking systems. In April 2025, Pierburg launched an electric vacuum pump in Germany focused on CO2 reduction and hybrid/brake system enhancement. May 2025 saw a cluster of launches: Bosch introduced its next-generation EVP for hybrid and electric vehicles; Denso launched a diaphragm-type EVP in Asia-Pacific for hybrid and ICE engines; and Continental unveiled a high-performance EVP for passenger ICE vehicles in Europe with adaptive vacuum control and regenerative braking integration. These moves indicate that product refresh cycles are accelerating, particularly around efficiency, control, and compliance.
Looking ahead, the competitive landscape is likely to evolve along three lines. First, consolidation may continue among suppliers that can offer integrated, compliant EVP systems with validated brake and powertrain compatibility. Second, differentiation will increasingly depend on control software, efficiency, and packaging flexibility rather than mechanical design alone. Third, new entrants and regional specialists will continue to challenge incumbents in specific applications, especially where cost, local supply relationships, or commercial-vehicle specialization provide a credible edge. The market is therefore not a simple two-tier hierarchy; it is a layered ecosystem in which both global scale and application-specific expertise create value.
Future Trends and Commercial Opportunities
Trend 1: Electric Vacuum Pumps as a Compliance and Efficiency Standard
As emissions and fuel economy mandates tighten, EVPs are likely to become a more standard element of vehicle design rather than a retrofit or niche solution. This trend is strongest in regions with aggressive regulatory timelines, but it is also spreading as automakers harmonize platforms across markets. The commercial opportunity lies in suppliers and OEMs that treat EVP integration as a system-level requirement from the outset, aligning pump selection with brake architecture, powertrain mode transitions, and thermal and packaging constraints. Early integration reduces redesign risk and supports compliance without compromising performance.
PW Consulting Automotive & Machinery Research Center
Trend 2: Adaptive, On-Demand Control as the Core Value Driver
The next phase of EVP competition will likely center on intelligent control: pumps that modulate output based on real-time demand, support regenerative braking coordination, and minimize power loss. This creates opportunities for suppliers that can combine hardware and control expertise, as well as for OEMs that can leverage adaptive vacuum management to improve efficiency and braking consistency across hybrid and electric modes. The value proposition is not simply “more vacuum,” but “vacuum delivered more precisely and with less energy cost.” As brake systems become more electrified and more dependent on coordinated control, this precision will increasingly differentiate suppliers.
Trend 3: Regional Specialization and Supply Chain Diversification
The market’s geographic distribution is likely to remain uneven, but regional specialization will become more important. Asia Pacific’s scale, Europe’s regulatory intensity, and North America’s mix of passenger and commercial requirements create distinct demand profiles. At the same time, suppliers that can serve multiple regions with adaptable product families and localized support will be better positioned to manage program risk and cost. Commercial opportunities include partnerships that combine global scale with regional responsiveness, and supplier strategies that balance cost efficiency with compliance readiness. Buyers benefit when they can access both mature, validated solutions and cost-competitive alternatives for less demanding applications.
Potential risks and uncertainties remain. Cost pressures may persist if raw material and manufacturing expenses do not decline as quickly as volume scales. Regulatory timelines can shift, altering the pace at which EVP integration becomes mandatory across additional vehicle categories. Platform fragmentation may also complicate standardization, especially when OEMs pursue diverse hybrid and electric strategies simultaneously. Finally, technological change in brake systems and electrification architectures could reshape the role of vacuum assist over time, making flexibility and monitoring essential for long-term planning.
Strategic Recommendations for Decision-Makers
For manufacturers and suppliers, the priority is to align EVP development with the regulatory and platform shifts that are shaping demand. This means investing in adaptive control, efficiency, and on-demand operation, while building product families that can serve ICE, hybrid, and electrified applications without excessive rework. Equally important is the ability to demonstrate system-level integration value, not just pump specifications. Suppliers that can show how their EVP solutions support braking performance, emissions compliance, and power efficiency in a coordinated architecture are more likely to win program contention in a concentrated market.
For investors, the EVP segment offers growth supported by regulatory tailwinds and electrification-linked demand, but selection matters. The most resilient opportunities are likely to be found in suppliers with credible hybrid/EV integration strategies, demonstrated compliance readiness, and the ability to compete across both premium and cost-sensitive applications. Monitoring product launch cadence, partnership activity, and regional supply relationships can provide early signals about which players are expanding their relevance and which are constrained to narrow niches. Given the market’s concentration and technical barriers, due diligence should focus on validation capability, control software development, and exposure to regulatory-driven demand across key regions.
For procurement and OEM strategy teams, the key is to avoid treating EVPs as interchangeable commodities. Specifications alone do not capture the value of adaptive control, integration compatibility, and compliance support. Procurement strategies should evaluate total system impact, including brake performance, energy consumption, packaging constraints, and lifecycle cost, while maintaining flexibility to source from both established incumbents and regional specialists where appropriate. In a market where cost remains a restraint but compliance and performance are non-negotiable, the best outcomes typically come from balancing proven system reliability with competitive cost structures.
The EVP market is moving from steady expansion to a more strategically nuanced phase, where regulation, electrification, and intelligent control redefine what suppliers must deliver and what buyers should prioritize. For organizations seeking more detailed segmentation data, company-level tracking, and customized assessments tailored to specific program portfolios or investment theses, the full research report provides a deeper dive into the numbers and the strategic implications behind them.
For detailed analysis of this topic, please visit the official page: Automotive EVP (Electric Vacuum Pump) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Inositol Market 2026: Why Plant Based Sources and 6.98% CAGR Reshape Strategy
By pmarketresearch, 2026-09-21
The Inositol Market: Strategic Trends and Commercial Opportunities Through 2032
The inositol market has transitioned from a niche biochemical ingredient to a strategically important segment within the broader nutritional and pharmaceutical supply chain. Valued at approximately $160.0 million in 2025, the market has expanded from $122.42 million in 2020, reflecting consistent demand growth across multiple downstream applications. Looking ahead, the trajectory points toward $255.82 million by 2032, with a compound annual growth rate of 6.98 percent. This expansion is not merely a function of population growth or generalized wellness trends. It reflects structural shifts in how manufacturers source active compounds, how regulators frame safety and labeling requirements, and how end users increasingly differentiate between synthetic and fermentation-derived alternatives.
For executives and strategic planners, the numbers tell only part of the story. The more critical question is what forces are reshaping competitive positioning, where margin pressure is emerging, and which capabilities will separate future leaders from followers. This analysis examines the market's core dynamics, the drivers accelerating change, the evolving competitive landscape, and the practical implications for manufacturers, investors, and procurement teams.
Market Context and Structural Challenges
The inositol market operates at the intersection of dietary supplements, pharmaceutical development, animal nutrition, and industrial applications. Demand is distributed across these segments, with dietary supplements and animal feed representing the largest application pools, followed by pharmaceutical use and other industrial or research-oriented applications. On the source side, plant-based production dominates supply, with animal-derived and synthetic routes occupying smaller but strategically important niches. Regional demand is balanced across North America, Europe, and Asia Pacific, with Latin America and the Middle East and Africa providing incremental growth corridors.
Despite this broad distribution, the market is not uniformly mature. Several structural challenges are shaping decision-making and forcing companies to reconsider sourcing strategies, product positioning, and compliance investments.
Raw Material Volatility and Sourcing Diversification
One of the most immediate pressures stems from input cost fluctuations. Rising corn prices through 2025 have prompted manufacturers to reconsider traditional feedstock dependencies and explore alternative raw material pathways. Rice bran and other plant-based inputs are increasingly being evaluated as viable alternatives for inositol extraction and fermentation processes. This diversification is not simply a cost-containment exercise. It reflects a broader recognition that feedstock concentration creates vulnerability, particularly when grain markets are influenced by weather patterns, trade policy shifts, or competing demand from biofuel and food sectors. Suppliers that can secure flexible sourcing agreements or invest in multi-feedstock fermentation capabilities are better positioned to stabilize margins and maintain consistent supply to downstream customers.
Regulatory Clarity and Compliance Burden
Regulatory developments are simultaneously creating opportunities and raising the bar for market participation. In the United States, the FDA's GRAS designation now permits inositol use in infant formula at defined dosage ranges of 4 to 40 milligrams per 100 kilocalories. This establishes a clearer pathway for manufacturers targeting the infant nutrition segment, but it also requires rigorous documentation, batch consistency, and labeling accuracy. In Europe, the European Food Safety Authority has confirmed inositol's safety profile with conservative dosing guidelines, which supports expanded applications while reinforcing the need for evidence-based positioning. At the same time, stricter compliance standards across dietary supplements and functional ingredients are encouraging manufacturers to invest more heavily in clinical research, transparency, and quality control. Companies that treat regulatory alignment as a strategic capability rather than a administrative hurdle are gaining trust with retailers, formulators, and end consumers.
Capacity, Purity, and Differentiation Pressure
The market's competitive structure remains moderately concentrated, with the top three players accounting for a combined share that reflects meaningful but not insurmountable barriers to entry. A CR3 of 35.6 percent and CR5 of 47.8 percent indicates that scale, technological capability, and application-specific expertise matter, but there is still room for specialized suppliers to compete on purity, sustainability, or niche performance characteristics. This dynamic creates pressure for mid-tier and emerging producers to articulate a clear value proposition. Suppliers offering generic bulk inositol face margin compression and customer switching risk, while those able to demonstrate fermentation-derived consistency, solvent-free processing, or application-tailored grades are better positioned to command premium positioning.
Core Drivers Reshaping the Market
The market's growth trajectory is being shaped by several interconnected forces. These drivers extend beyond basic demand expansion and reflect deeper changes in technology, regulation, consumer behavior, and supply chain economics.
1. Fermentation Technology and Sustainable Production Pathways
Technological progress in fermentation has emerged as a defining shift in how inositol is produced and positioned. Traditional extraction and chemical synthesis routes are increasingly being complemented, and in some cases displaced, by fermentation-based processes that offer higher purity, reduced solvent use, and more consistent batch profiles. The commercial launch of solvent-free fermented myo-inositol and the introduction of fermented D-chiro-inositol represent meaningful milestones. These products are being positioned as cleaner, sustainable alternatives for nutraceutical and health-focused formulations, aligning with broader industry expectations around ingredient transparency and environmental impact.
Strategic partnerships are reinforcing this trajectory. Collaborations between biotechnology developers and established chemical or industrial partners are accelerating process optimization and creating pathways for higher-volume production of fermentation-derived intermediates. For market participants, the implication is clear: fermentation capability is becoming a differentiator not just for environmental messaging, but for performance consistency, regulatory positioning, and appeal to formulators seeking cleaner ingredient profiles.
2. Regulatory Alignment and Application Expansion
Regulatory clarity is unlocking new application pathways while simultaneously raising quality expectations. The FDA's guidance on infant formula use and EFSA's supportive safety confirmation are examples of how regulatory frameworks can broaden addressable markets when manufacturers have the documentation and quality systems to meet requirements. These developments are particularly significant for companies targeting early-life nutrition, specialized dietary supplements, and pharmaceutical-adjacent applications where safety and traceability are non-negotiable.
At the same time, tighter compliance expectations are driving investment in clinical research and product transparency. Manufacturers are increasingly expected to substantiate functional claims, provide batch-level consistency, and maintain clear documentation across the supply chain. This environment favors companies that integrate quality, research, and regulatory affairs into their commercial strategy rather than treating them as back-office functions.
3. Demand-Side Shifts Toward Wellness, Metabolic Health, and Specialty Nutrition
End-user demand is evolving along several axes. In dietary supplements, growing consumer awareness of metabolic health, stress response, and hormonal balance has increased interest in inositol as a functional ingredient. In animal nutrition, the push toward improved gut health, feed efficiency, and alternatives to antibiotic growth promoters is expanding the relevance of inositol in feed formulations. Pharmaceutical and research applications continue to require high-purity grades for development and specialized use.
These demand-side shifts are not uniform, but they share a common thread: end users are increasingly selective about ingredient origin, purity, and supporting evidence. Brands and formulators are looking for suppliers that can provide not only consistent material, but also the technical support, regulatory documentation, and application expertise needed to integrate inositol effectively into finished products.
Inulin Market
4. Supply Chain Reconfiguration and Cost Structure Realignment
The inositol supply chain is being reshaped by feedstock dynamics, regional production capabilities, and the cost implications of different manufacturing routes. As corn-based inputs face price volatility, manufacturers are diversifying toward rice bran and other plant-based materials, while fermentation-based producers are investing in scale and process efficiency. These shifts are changing the relative economics of plant-based extraction, animal-derived sourcing, and synthetic production.
For procurement and supply chain teams, the practical implication is that supplier resilience now depends on feedstock flexibility, geographic diversification, and the ability to maintain quality across alternative inputs. Suppliers that can demonstrate robust sourcing strategies and consistent processing standards are better equipped to support long-term customer relationships in a volatile input environment.
Competitive Landscape and Strategic Positioning
The competitive field in the inositol market includes large-scale producers, specialized fermentation developers, established distributors, and research-grade suppliers. The diversity of players reflects the broad application base, but it also means that competitive advantage increasingly depends on how companies align their capabilities with specific customer needs and market segments.
Scale, Fermentation Expertise, and Global Supply
Several Chinese manufacturers have built significant capacity around plant-based myo-inositol and derivatives, including D-chiro-inositol and scyllo-inositol, produced via fermentation and supplied globally for supplements, pharmaceuticals, food, and animal nutrition. With annual capacity reaching thousands of tons in some cases, these suppliers compete on scale, cost efficiency, and the ability to serve multiple downstream markets. Their strategic positioning often emphasizes fermentation know-how, high-purity output, and broad application coverage. For customers seeking reliable volume supply across multiple formats, these players offer an attractive combination of capacity and versatility.
Other regional producers are similarly focused on fermentation-derived inositol and derivatives for dietary supplements, infant nutrition, and feed applications, with an emphasis on high-purity processes. Their value proposition centers on application-specific consistency and the ability to support specialized nutrition segments with controlled-quality material.
Sustainable Innovation and Product Differentiation in Advanced Markets
In the United States and Europe, a different competitive dynamic is emerging around sustainability, purity, and application-specific innovation. Manufacturers and distributors of bulk inositol powder and graded materials for nutritional, pharmaceutical, and industrial uses are active in supplying established markets with reliable volumes and clearly defined specifications. Some focus on whole-food nutritional supplements, offering plant-based inositol for wellness and dietary applications, while others serve industrial and research channels with ISO-certified chemical supply and laboratory-grade material.
D-Mannose Market
A particularly notable strategic move has come from biotechnology developers commercializing solvent-free fermented myo-inositol and industry-first fermented D-chiro-inositol as cleaner, sustainable alternatives for nutraceutical formulations. These launches are not just product additions; they represent a positioning strategy centered on sustainability, higher purity, and alignment with health-focused brands that value fermentation-derived ingredients. Partnerships with established industrial players further reinforce the credibility and scalability of these processes, signaling that fermentation-based differentiation is increasingly integrated into broader supply chain strategies rather than treated as a standalone innovation experiment.
PW Consulting
Research-Grade Suppliers and the High-Purity Segment
Several suppliers specializing in laboratory-grade and API inositol for research, pharma, and biotech applications occupy an important niche. These companies focus on high-purity biochemicals for development, analytical work, and specialized formulations. Their competitive advantage lies in quality documentation, consistency, and the ability to support technically demanding customers. For pharmaceutical developers, research institutions, and biotech teams, these suppliers provide the reliability and specification control required for advanced applications, even if their volumes are smaller relative to bulk nutrition and feed channels.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The market's structure suggests multiple concurrent trends. On one hand, scale advantages in fermentation and bulk supply are encouraging consolidation among larger producers seeking to strengthen cost positions and global reach. On the other hand, the demand for specialized grades, sustainable sourcing, and application-specific support is sustaining a fragmented layer of niche suppliers and regional specialists. New entrants are likely to focus on fermentation innovation, solvent-free processes, or targeted application segments where purity and documentation create defensible positioning. The overall trajectory points toward a market where broad-scale suppliers and specialized innovators coexist, with competitive success determined by how well each aligns its capabilities with the expectations of its chosen customer base.
Forward Outlook: Trends and Commercial Implications
The next three to five years are likely to be defined by several interconnected trends that will shape both opportunity and risk for market participants.
1. Fermentation-Derived and Solvent-Free Products Will Gain Share in Premium Segments
As sustainability expectations rise and formulators seek cleaner ingredient profiles, fermentation-derived inositol and solvent-free processes are poised to capture greater attention in nutraceutical, wellness, and specialty nutrition applications. This trend will not eliminate extraction or synthetic routes across all segments, but it will increasingly differentiate premium offerings and influence procurement decisions among brands that prioritize transparency and environmental positioning. Companies that can demonstrate scalable fermentation capability, consistent purity, and credible sustainability claims will be best positioned to benefit from this shift.
2. Regulatory-Driven Application Expansion Will Open New Demand Pools
The combination of clearer regulatory guidance in the United States and Europe, along with growing interest in infant nutrition, metabolic health, and functional supplements, is likely to expand the addressable market beyond current baselines. Suppliers that invest in documentation, quality systems, and application support will be better equipped to enter these higher-value segments. The opportunity is not simply to sell material, but to provide the regulatory and technical scaffolding that allows customers to use inositol confidently in sensitive or regulated applications.
3. Feedstock Flexibility and Supply Chain Resilience Will Become Competitive Essentials
As input cost volatility persists and manufacturers diversify away from single-feedstock dependencies, the ability to maintain consistent quality across alternative raw materials will become a key differentiator. Supply chain resilience will increasingly be evaluated not just on price, but on sourcing flexibility, geographic diversification, and the ability to guarantee batch consistency under changing input conditions. Companies that build these capabilities into their operating model will be more reliable partners for customers operating in regulated or quality-sensitive environments.
Risks and Uncertainties
Several uncertainties could alter the trajectory described above. Feedstock price swings could compress margins or delay investment in alternative sourcing if volatility proves more persistent than expected. Regulatory environments may shift as authorities revisit dosing guidance, labeling expectations, or safety thresholds, particularly in sensitive applications such as infant nutrition. Competitive entry in fermentation-based production could intensify price competition in premium segments if new capacity outpaces demand growth. Finally, if clinical evidence or consumer perception does not keep pace with product launches, some innovation-driven positioning may face headwinds. Companies should monitor these variables closely and build flexibility into both sourcing and product strategy.
Actionable Guidance for Decision-Makers
The strategic implications differ depending on a company's role in the value chain, but several priorities are broadly relevant.
For Manufacturers and Producers
- Evaluate feedstock diversification as a strategic capability, not just a cost initiative. Multi-source strategies and flexible fermentation or extraction pathways can reduce exposure to commodity volatility and improve supply reliability.
- Invest in fermentation capability and solvent-free or high-purity processes where they align with target customer expectations. Differentiation in sustainability and purity is increasingly tied to commercial positioning in premium nutrition and pharmaceutical-adjacent markets.
- Strengthen quality documentation, regulatory support, and application expertise. Customers in regulated or quality-sensitive segments are looking for suppliers that can provide more than material; they want partners who can support formulation, compliance, and consistency.
For Investors
- Focus on companies with clear technological differentiation, scalable fermentation or production capabilities, and credible pathways into higher-value applications. Volume alone is less compelling than the ability to command premium positioning through purity, sustainability, or application support.
- Monitor regulatory developments as indicators of where demand is likely to expand. Clear guidance in infant nutrition, dietary supplements, and functional ingredients can signal near-term opportunity for suppliers with the right documentation and quality systems.
- Assess supply chain resilience and feedstock strategy as part of long-term risk evaluation. Companies that depend on a single input route or lack flexibility may face margin and continuity risk if commodity conditions shift.
For Procurement and Formulators
- Prioritize supplier resilience and quality consistency over short-term price advantages. In regulated or quality-sensitive applications, batch consistency, documentation, and sourcing transparency can reduce downstream risk and protect brand reputation.
- Engage suppliers early on application requirements, regulatory documentation, and technical support. The most valuable partnerships are built on alignment around purity, grade specifications, and the evidence or compliance support needed for the target market.
- Track fermentation-derived and solvent-free options as potential differentiation levers for product positioning. Where sustainability or cleaner ingredient narratives matter to end users, these alternatives may offer strategic value beyond basic material supply.
Closing Perspective
The inositol market is moving from a broadly functional ingredient space toward a more differentiated landscape shaped by fermentation innovation, regulatory clarity, feedstock dynamics, and evolving end-user expectations. The growth trajectory through 2032 reflects genuine expansion, but the commercial opportunity will be captured by companies that treat quality, sustainability, regulatory alignment, and supply resilience as strategic capabilities rather than operational details.
For organizations seeking deeper segmentation data, company-level benchmarking, region-specific demand patterns, and tailored strategic recommendations, the full PW Consulting research report provides a more granular view of the market and its participants.
For detailed analysis of this topic, please visit the official page: Inositol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ethylene Oxide Market: Why the 4.22% CAGR Trajectory Changes Everything
By pmarketresearch, 2026-09-21
Navigating the Ethylene Oxide Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Snapshot and Structural Dynamics
The global ethylene oxide (EO) market has demonstrated consistent expansion over the past half-decade, advancing from approximately $33.9 billion in 2020 to an estimated $41.7 billion in 2025. Projections indicate the market will reach roughly $55.7 billion by 2032, reflecting a compound annual growth rate of 4.22 percent across the forecast window. This trajectory underscores a resilient demand environment that continues to absorb incremental capacity, regulatory friction, and supply chain recalibrations without losing momentum. The underlying composition of value creation remains heavily weighted toward derivative chemistry, with a single downstream family accounting for the majority of volume conversion, while sterilization and specialty applications carve out a strategically critical but smaller share of total throughput.
Current market dynamics reveal two structural tension points that will define investment and operational decisions over the next several years. The first revolves around regulatory intensity targeting commercial sterilization operations, particularly in North America, where emission standards and permitting frameworks have tightened considerably. Facilities have responded by investing in containment engineering, permitting new sites, or adjusting operational footprints, but the pace and durability of compliance adjustments remain uneven across jurisdictions. The second tension lies in regional demand asymmetry. Asia Pacific has emerged as a high-growth conversion hub, driven by expanding polyester and antifreeze/coolant capacity, while mature regions are increasingly focused on high-margin medical and specialty applications rather than bulk commodity margins. This divergence is reshaping how producers allocate merchant-grade material and how sterilization service providers site their processing networks.
A third inflection point sits at the intersection of feedstock economics and end-use substitution pressure. Ethylene oxide pricing and availability are tightly coupled to upstream ethane and ethylene markets, which means cost structures can shift quickly when regional energy dynamics move. At the same time, certain downstream segments are experimenting with alternative sterilization modalities or material substitutions, especially where regulatory exposure and community emissions concerns create operational uncertainty. The result is a market that is still growing, but one in which growth is increasingly contingent on operational discipline, compliance readiness, and differentiated service capabilities rather than volume alone.
Key Drivers Reshaping the Ethylene Oxide Value Chain
Technology and Process Innovation
Innovation in EO handling, sterilization processing, and derivative conversion is moving from incremental improvement toward capability redefinition. On the sterilization side, service providers are increasingly combining EO cycles with complementary modalities such as gamma radiation and vaporized hydrogen peroxide to widen the range of sterilizable materials and reduce cycle times for mixed product portfolios. This hybrid approach matters because medical device manufacturers increasingly ship complex assemblies, polymer components, and temperature-sensitive instruments that cannot tolerate uniform treatment protocols. By layering sterilization technologies under one service framework, providers can offer design-for-sterilization guidance and post-processing validation that become value-added differentiators rather than commoditized throughput services.
In the derivative space, conversion efficiency and purity specifications are becoming more tightly linked to application performance. Ethylene glycols and glycol ethers continue to anchor large-scale industrial and consumer demand, but the highest-value niches are concentrating around ultra-pure grades for medical sterilization and specialty ethoxylates and ethanolamines used in formulation chemistry. Operators that can guarantee consistent purity, traceability, and lot-level documentation are gaining preferential access to regulated applications, which in turn raises the operational bar for newer entrants and rewards established facilities with mature quality systems and engineering depth.
Regulatory and Compliance Environment
Regulatory evolution remains the single most consequential variable for commercial sterilization operations. Recent EPA proposals to amend existing emission standards for commercial sterilization facilities reflect a deliberate balancing act: preserving the availability of life-saving devices that depend on EO sterilization while addressing community exposure concerns. The proposed adjustments, which include discussions around permanent total enclosure requirements and other operational conditions, signal that regulators are actively recalibrating compliance burdens in response to supply chain risk considerations. This matters commercially because sterilization capacity is not easily relocated or rapidly duplicated; permitting timelines, community engagement, and engineering retrofits can stretch project schedules and alter site economics.
Beyond federal action, state and local air quality programs continue to influence operating conditions, and enforcement outcomes can reshape community expectations and facility siting strategies. The trend is not a blanket regulatory contraction; rather, it is a selective tightening that creates compliance winners and losers. Operators with robust emissions control engineering, transparent monitoring practices, and documented safety governance are better positioned to sustain operating continuity. Conversely, facilities that rely on legacy configurations without proactive upgrade planning face greater uncertainty in permitting renewals, expansion approvals, and long-term site viability.
Demand-Side Shifts in Medical Devices and Industrial Applications
Demand behavior is bifurcating across application clusters. In medical and pharmaceutical channels, EO remains deeply embedded in sterilization workflows for in vitro diagnostics, catheters, syringes, disposable consumables, and other temperature-sensitive devices. The scale of this dependency reinforces the strategic importance of reliable sterilization capacity, particularly when device complexity increases and manufacturers require validated, repeatable processes with strong documentation support. As device portfolios diversify, sterilization is increasingly treated as an extension of product design and quality assurance, not simply a finishing step. This creates commercial opportunities for service providers that can align sterilization protocols with device development cycles and regulatory submissions.
Polyethylene Oxide (PEO) Market
On the industrial side, polyester fiber and PET resin production continue to anchor large-volume EO derivative demand, supported by apparel, packaging, and industrial polyester applications. Antifreeze and coolant formulations also remain substantial consumer of ethylene glycol derivatives, with demand tied to automotive, HVAC, and industrial machine cooling needs. While these bulk segments are more price-sensitive and cyclical than medical sterilization, they still provide the volume foundation that supports merchant EO economics. The strategic implication is that producers and converters must manage a dual rhythm: disciplined execution in cyclical commodity demand, and premium positioning in regulated, specification-driven applications that carry higher switching costs.
Ethanolamine Market
Supply Chain Reconfiguration and Cost Structure Dynamics
Cost and supply dynamics are increasingly influenced by geographic concentration in feedstock access and conversion capacity. Regional production clusters have shaped short-term availability and pricing behavior, with merchant EO distribution dependent on logistics, storage, and site-level handling standards. Because EO is both reactive and hazardous, the cost structure extends beyond raw material pricing to include safety systems, certification, transport controls, and insurance exposure. As a result, the economics of EO supply are highly sensitive to operational maturity and regional infrastructure quality, which gives established producers and integrated service networks a structural advantage in stable service delivery.
At the same time, sterilization demand for ultra-pure grades creates a specialized supply track that operates with higher quality and handling requirements than merchant commodity streams. This bifurcation means that the same molecule can command very different commercial treatment depending on application class, documentation needs, and compliance posture. Companies that can cleanly separate operational lanes, manage purity assurance, and maintain reliable throughput under tighter handling protocols are better positioned to capture margins in regulated segments, while commodity-focused players must compete more aggressively on availability, flexibility, and cost discipline.
Competitive Landscape and Strategic Positioning
How Leading Players Differentiate
The competitive field spans producers, sterilization service providers, and device manufacturers that intersect with EO across different segments of the value chain. Core enterprise profiles reveal three broad strategic orientations. Some organizations focus on high-purity medical-grade EO packaged for low-temperature sterilization of sensitive devices, emphasizing purity assurance, packaging integrity, and service support for regulated applications. Others position around contract sterilization services, offering validated processing in compliance with recognized sterilization standards and building multi-facility networks that can serve device manufacturers at scale. A third group includes large device manufacturers and diversified industrial players that use EO sterilization as part of their product delivery or supply operations, often embedding sterilization strategy into broader quality and regulatory planning.
Within this landscape, differentiation is increasingly driven by compliance capability, geographic reach, and service integration rather than by feedstock ownership alone. Sterilization providers that invest in validated protocols, engineering support, and emissions management can reduce the operational risk that device manufacturers are increasingly unwilling to absorb internally. Producers that supply merchant-grade EO benefit from volume stability in bulk derivative markets, but their strategic leverage grows when they can reliably serve regulated sterilization demand with consistent quality and logistics reliability. Device manufacturers that oversee their own sterilized product lines gain advantage by aligning material selection, packaging, and sterilization validation early in development, which can shorten qualification cycles and reduce downstream processing risk.
Recent operational moves illustrate these choices in practice. New sterilization facility construction in growth regions reflects the push to place capacity closer to expanding medical device and diagnostics manufacturing bases. Simultaneously, technology combinations that blend EO with other sterilization modalities are being introduced to accommodate broader material compatibility and sterility assurance requirements. Regulatory and legal resolutions around permitting and emissions have also become part of the strategic picture, reminding the market that operating license stability, community relations, and documented compliance practices are now central to long-term commercial viability.
PW Consulting
Market Structure Evolution
Market concentration remains relatively high, with a limited number of large players accounting for a substantial share of total value. That concentration is most visible in bulk derivative supply, where scale economics and feedstock access shape the competitive field. In sterilization services, the structure is more fragmented across geographies and facility networks, but consolidation trends are emerging where integrated service capabilities, multi-site footprints, and compliance infrastructure create defensible positions. The resulting landscape is neither purely consolidated nor purely dispersed; it is stratified, with commodity supply leaning toward scale concentration and specialized sterilization and device-related applications trending toward capability-driven consolidation.
The evolution trajectory suggests a continued pull toward operational maturity thresholds. New entrants will find it difficult to compete on pure price in regulated sterilization markets because qualification, documentation, emissions control, and long-term reliability create high switching costs for customers. At the same time, regional demand growth can still invite capacity additions in conversion and derivatives, especially where local polymer, packaging, and antifreeze demand expands. The practical outcome is a market where strategic advantage accrues to firms that combine scale, quality systems, compliance readiness, and proximity to end-use demand clusters, while generic capacity without differentiated execution faces margin compression and higher operational risk.
Forward Outlook: Three Trends Shaping 2027 to 2032
Trend One: Sterilization as a Stabilized Strategic Capability
Over the next several years, EO sterilization is likely to become more institutionalized as a specialized capability rather than a commoditized service. The combination of device complexity, regulatory scrutiny, and the continued scale of EO-dependent sterilization supports this direction. Providers that invest in standardized protocols, hybrid sterilization options, emissions engineering, and transparent compliance reporting will be better positioned to secure multi-year service relationships and reduce customer-side operational burden. The commercial opportunity lies not just in processing volume but in becoming a partner in device qualification, packaging design, and supply continuity, which can create stickier demand and more predictable revenue streams.
Trend Two: Regional Rebalancing of Conversion and Service Capacity
Demand growth will continue to be uneven geographically, and capacity expansion will follow end-use momentum rather than uniform global growth rates. Asia Pacific and other developing industrial regions will likely remain focal points for derivative expansion, particularly in polyester and coolant-related applications, while North America and Europe will keep attention on higher-value medical device sterilization and specialty derivatives. This rebalancing creates opportunities for companies that can site capacity intelligently, manage cross-border logistics for merchant EO, and align service networks with regional device manufacturing density. It also introduces risk for operators who assume demand migration will be linear; regional policy shifts, energy cost changes, and local permitting environments can alter the attractiveness of specific sites or expansion plans.
Trend Three: Compliance Discipline as a Margin Determinant
As emissions expectations and community oversight remain elevated in several jurisdictions, compliance performance is increasingly becoming a margin determinant rather than a back-office operational issue. Facilities that proactively manage containment, monitoring, permitting documentation, and community engagement will face lower interruption risk and stronger negotiating positions with regulators and customers. Conversely, facilities that treat compliance improvements as reactive or episodic will face greater exposure to enforcement actions, operational pauses, and reputational friction. The strategic implication is that capital allocation toward safety, engineering, and compliance infrastructure should be modeled as a growth enabler, not merely a cost center, especially for operations tied to regulated medical applications.
Strategic Actions for Decision Makers
For Manufacturers and Service Providers
Design EO-related operations around two parallel mandates: reliability in regulated applications and cost discipline in bulk derivative markets. For sterilization services, prioritize validated processing frameworks, hybrid modality flexibility, emissions engineering, and documentation quality that supports device manufacturers across qualification and production cycles. For derivative producers, sharpen purity assurance and lot-level traceability where premium grades command stronger positioning, while preserving operational efficiency in commodity conversion. Where expansion is contemplated, sequence site decisions around end-use density, permitting feasibility, and logistics reliability rather than treating capacity additions as purely volume-driven responses.
Strengthen supply resilience by clarifying which customer segments depend on merchant EO availability versus ultra-pure sterilization grades, then align inventory, handling, and distribution practices accordingly. Build contingency planning for feedstock price volatility and regional energy shifts, since those variables can quickly change margin profiles even when end-demand remains stable. Treat safety, compliance, and emissions management as core competencies that influence customer selection, permitting speed, insurance conditions, and long-term site viability.
For Investors
Screen opportunities through a lens of operational maturity and regulatory exposure, not just top-line growth potential. In sterilization-linked operations, assess emissions control capability, facility siting strategy, compliance documentation, and the degree to which the business is integrated with device qualification and service continuity. In producer and derivative conversion businesses, evaluate feedstock access, regional cost structure, purity capability for premium grades, and exposure to cyclical demand swings in polyester, antifreeze, and coolant markets. The highest-risk exposures often sit where compliance, permitting, or community relations are under-managed, even if revenue growth appears attractive in the near term.
Look for businesses that are converting regulatory pressure into durable competitive advantage by investing in engineering, monitoring, and multi-modality service options. In growth regions, distinguish between genuine demand-led expansion and speculative capacity additions; the former tends to be supported by local manufacturing density and downstream application growth, while the latter may face margin pressure if supply outpaces absorption. Finally, monitor where hybrid sterilization services and premium-grade handling create switching costs that protect revenue quality, since those are the segments most likely to sustain differentiated returns through cycles.
For Procurement and Supply Chain Leaders
Treat EO-dependent supply as a strategic continuity issue rather than a routine commodity purchase. Where medical devices, diagnostics, or temperature-sensitive materials depend on EO sterilization, validate supplier readiness across validation support, emissions posture, facility redundancy, and documentation quality. For industrial derivative procurement, focus on availability reliability, specification consistency, and logistics controls that account for hazardous-material handling and regional supply access. Diversifying processing routes or site options where feasible can reduce concentration risk, but only if alternative sources meet the same quality and compliance expectations required by your applications.
Incorporate compliance and operational resilience questions into supplier evaluation, including evidence of emissions management practices, permitting status, safety governance, and continuity planning. For categories where substitution or alternative sterilization modalities are technically feasible, run structured cost and risk comparisons rather than assuming price alone determines the best choice. In many cases, the lowest apparent unit cost can be offset by qualification delays, documentation gaps, or interruption risk in regulated supply chains.
From Market Intelligence to Execution
The ethylene oxide market is expanding, but the character of that expansion is changing. Growth is increasingly governed by compliance readiness, product complexity, regional end-use demand, and the ability to deliver reliable service across both regulated and commodity segments. Firms that understand these operating realities can align capacity, service models, and procurement strategies with where value is actually being created, rather than assuming that volume growth will automatically translate into favorable outcomes.
For teams that need a deeper, segment-level view of regional demand patterns, derivative conversion splits, application drivers, competitive footprints, and scenario-based sizing through 2032, the comprehensive PW Consulting research report provides detailed data and customized recommendations designed for implementation planning.
For detailed analysis of this topic, please visit the official page: Ethylene Oxide (EO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Peripheral Guidewire Market: 7.8% CAGR Trajectory Signals Shifting Value Pools
By pmarketresearch, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Peripheral Guidewire Market
The peripheral guidewire market has entered a phase of sustained expansion, underpinned by consistent revenue growth across the 2020–2025 period and a robust projected trajectory through 2032. Market size evolved from approximately $123.45 million in 2020 to $151.08 million in 2023, accelerating to $168.47 million in 2025. The forecast period from 2026 to 2032 projects a compound annual growth rate of 7.8 percent, with valuations scaling toward $283.0 million by the end of the horizon. This trajectory reflects not merely incremental expansion but a structural redefinition of how clinicians navigate peripheral vascular disease, diagnostic pathways, and minimally invasive interventions. For executives and investors, the market presents a maturing landscape where differentiation hinges on material science, regulatory agility, and partnership-driven distribution rather than volume alone.
Despite the positive momentum, the industry faces structural tensions that will shape competitive outcomes over the next five years. First, the balance between standardization and specialization remains unresolved. Guidewires must deliver reliable trackability and pushability across diverse anatomical targets, yet the proliferation of lesion complexity, smaller vessel diameters, and transradial access protocols demands tailored performance profiles. Second, regulatory harmonization is intensifying compliance costs while simultaneously raising barriers to entry for fragmented suppliers. The alignment of quality management systems with ISO 13485:2016 and the continued reliance on 510(k) pathways for device iterations create a dual dynamic: predictable clearance routes for incremental innovations, but elevated scrutiny for novel material combinations or performance claims. Third, reimbursement environments and hospital cost-containment programs are pressuring procurement teams to justify premium device selections, pushing manufacturers to demonstrate clinical outcomes, reduced procedure time, or lower complication rates to sustain pricing power.
Technology Innovation and Material Performance
Material science continues to anchor the market’s evolution. Nitinol-based constructions dominate performance-sensitive applications due to their superelastic properties and resistance to kinking, while stainless steel retains a strong foothold for routine procedural navigation where cost efficiency and torque control are prioritized. Composite architectures are gaining traction in scenarios requiring balanced flexibility and column strength, particularly where hydrophilic coatings and jacketed designs enhance lubricity without compromising tactile feedback. Innovation is increasingly moving toward micro-scale engineering: micro-cut nitinol sleeves, targeted coil geometries, and precision-layered jackets are enabling guidewires that maintain luminal support in smaller vessels while improving deliverability through tortuous anatomy. These advances are not cosmetic; they translate into longer device longevity, reduced procedural friction, and expanded use cases that blur the boundary between diagnostic traversal and interventional support.
Regulatory Environment and Quality System Alignment
The regulatory landscape is evolving from fragmented national expectations toward more converged quality frameworks. The finalization of quality management system rules aligning with ISO 13485:2016 has consolidated expectations around design control, risk management, and post-market surveillance, providing a clearer compliance pathway for manufacturers that invest early in standardized processes. Concurrently, 510(k) clearances for peripheral and neurovascular guidewires remain a practical route for incremental product iterations, but the emphasis on substantial equivalence and performance comparability means that innovation must be framed within demonstrable clinical or usability advantages. For companies operating across regions, the divergence in certification timelines—exemplified by CE MDR approvals and U.S. clearances—requires portfolio planning that anticipates geographic sequencing, not just device readiness.
Guide Wires Market
Demand-Side Shifts in Clinical Practice
Clinical adoption patterns are reshaping demand. Transradial access has expanded beyond coronary interventions, with growing interest in peripheral artery disease procedures that prioritize patient comfort, reduced bleeding complications, and faster recovery. At the same time, interventional volumes in lower extremity disease are rising as population risk factors persist and image-guided techniques improve procedural confidence. The convergence of these trends puts pressure on guidewire portfolios to support both diagnostic navigation and interventional maneuvering, often within a single procedural workflow. Hospital administrators and procurement committees increasingly evaluate device choices through the lens of procedure efficiency, compatibility with existing catheter systems, and the ability to reduce device swaps or redundant access attempts. Consequently, guidewire value propositions that emphasize reliability, trackability, and procedural versatility are gaining procurement attention.
Supply Chain and Cost Structure Pressures
Manufacturing complexity, raw material variability, and sterilization requirements continue to influence cost structures. The competitive intensity reflected in a moderately concentrated market—with the top three and top five players holding a modest combined share—indicates room for specialization but also rewards scale advantages in sourcing, testing, and quality assurance. Companies that can manage coating consistency, coil precision, and device finishing at scale are better positioned to absorb compliance overhead while maintaining margin integrity. At the same time, distribution strategies are becoming a more meaningful lever: exclusive partnerships and regional commercialization agreements allow established players to expand portfolios without proportionally increasing internal manufacturing footprint, while smaller innovators leverage targeted approvals to enter high-value markets with focused product lines.
Competitive Landscape and Leading Strategies
The competitive field combines multinational device platforms with specialized manufacturers and regional innovators, each pursuing distinct strategic positions. Abbott Laboratories provides a peripheral vascular intervention portfolio focused on support and navigation wires for lower extremity procedures, positioning itself around clinical familiarity and broad procedural coverage. Boston Scientific Corporation has emphasized challenging small vessel and peripheral artery disease interventions through dedicated lines, reinforcing a strategy centered on deliverability in complex anatomy. Terumo Corporation offers hydrophilic and specialty guidewires for interventional cardiology and peripheral procedures, leveraging coating technology and navigation feel as differentiators. Medtronic plc supplies peripheral guidewires for transradial access in peripheral artery disease treatment, aligning product design with the broader shift toward radial workflows. Asahi Intecc Co., Ltd. focuses on trackability and durability for PTA and PPI procedures, emphasizing precision engineering in repeat-use scenarios. Cook Medical LLC extends peripheral guidewire portfolios across urology, gastroenterology, and vascular access, reflecting a cross-specialty distribution logic rather than a single-vascular focus. B. Braun Melsungen AG designs guidewires for safe catheter placement in peripheral procedures, emphasizing controlled access and procedural safety. Merit Medical Systems, Inc. delivers high-precision guidewires across cardiovascular, peripheral, radiology, and urology interventions, supporting a diversified interventional footprint. Biotronik SE & Co. KG provides vascular access and intervention guidewires, adding to the regional and specialty coverage mix. CONMED Corporation manufactures guidewires and related peripheral intervention tools, while Cardinal Health, Inc. distributes guidewire products through its Cordis division for peripheral vascular procedures. Specialty and emerging players such as LA Vascular, Future Medical Design Co., Ltd., and BrosMed Medical illustrate a parallel layer of targeted innovation and regional commercialization.
Worldwide Wedge Pressure Catheter Market
Differentiation Through Product Architecture and Access Strategy
Leading strategies are bifurcating around two complementary models. The first is portfolio depth within a defined clinical pathway: companies invest in multiple diameters, tip designs, coating options, and support profiles to cover diagnostic traversal, lesion crossing, and post-dilation support. The second is targeted expansion through distribution and co-commercialization, where established platforms extend their reach by licensing or exclusively distributing specialized guidewires that complement existing procedural lines. Both approaches aim to reduce the need for clinicians to switch vendors mid-procedure, a practical driver of preference and order consistency. Differentiation is increasingly less about claiming generic superiority and more about demonstrating that a particular combination of tip stiffness, shaft flexibility, coating behavior, and compatibility with catheter systems solves a specific procedural bottleneck.
Market Evolution: Consolidation, Niche Focus, and New Entrants
The market structure suggests gradual consolidation in distribution and service delivery, but persistent fragmentation in product specialization. Incumbents benefit from clinician relationships, established training ecosystems, and the credibility of broad intervention portfolios, which strengthens repeat procurement. At the same time, niche players continue to enter with focused designs, CE MDR approvals, or 510(k) clearances that unlock regional opportunities. This dynamic creates a two-speed environment: large players compete on breadth, service, and procedural integration, while smaller entrants gain traction by addressing specific anatomical challenges, access routes, or coating preferences. Over time, the most resilient portfolios will likely combine internal engineering with selective partnership-driven expansion, balancing fixed cost exposure with the agility to enter new procedural niches.
Future Trends and Commercial Implications
Several trends are likely to shape the market over the next three to five years. First, the integration of guidewire performance with procedure efficiency will intensify. Devices that reduce navigation time, improve lesion access, or lower the likelihood of device exchange will be valued not only for clinical outcomes but also for throughput and resource utilization. Second, transradial and small-vessel access will continue to expand peripheral use cases, encouraging designs that preserve tactile feedback while supporting finer delivery systems. Third, the regulatory and quality environment will reward manufacturers that have already institutionalized ISO-aligned processes and can respond quickly to clearance requirements, potentially favoring organizations with disciplined design controls and documented performance comparability. These trends collectively point toward a market where technical performance, procedural fit, and commercial execution matter as much as raw device approval.
Commercial opportunities will accrue to companies that align product development with procurement realities. For manufacturers, the value proposition will increasingly include evidence of procedural reliability, compatibility with existing access systems, and a clear mapping to lesion complexity and vessel size. For investors, the market’s moderate concentration invites attention to firms that can convert specialized approvals into regional scale, and to platforms that use distribution agreements to extend portfolio breadth without proportionate manufacturing expansion. For procurement and clinical leaders, the opportunity lies in standardizing around guidewires that demonstrably reduce procedural friction, while maintaining flexibility for complex cases that require alternative support profiles. Potential risks include reimbursement variability that compresses device budgets, regulatory timeline shifts that delay regional launches, and material or coating consistency challenges that can affect device performance consistency at volume.
Strategic Actions for Decision-Makers
Guidance for Manufacturers
Product roadmaps should prioritize features that translate directly into procedural value: predictable trackability in tortuous anatomy, reliable torque transfer, and coating behavior that supports smooth advancement without compromising tactile control. Regulatory planning should treat geographic sequencing as a commercial decision, aligning approval timing with distribution readiness and clinician training capacity. Where internal scale is limited, selective distribution partnerships can accelerate market access while preserving engineering focus on performance differentiation. Quality systems should be designed with anticipated clearance expectations in mind, ensuring that design history, risk documentation, and performance comparability are ready when submission windows open.
PW Consulting
Guidance for Investors
Investment attention should focus on companies that demonstrate a credible path from product approval to commercial execution, particularly where regional clearance events can unlock share in targeted markets. The combination of moderate concentration and active specialty entrants suggests that value will emerge from execution discipline rather than broad market exposure alone. Distribution agreements and exclusive partnerships can be meaningful indicators of commercialization intent, but they should be evaluated alongside manufacturing readiness, service infrastructure, and the clarity of the underlying procedural need. Portfolio breadth is valuable, but breadth without procedural fit or reliable supply can dilute returns.
Guidance for Procurement and Clinical Strategy Leaders
Procurement strategies should weigh guidewire selection against total procedural impact, including navigation reliability, compatibility with existing catheter systems, and the likelihood of reducing device swaps in complex cases. Standardization where clinically appropriate can improve efficiency and inventory management, while maintaining access to specialty designs for challenging anatomy preserves procedural flexibility. Supplier evaluation should incorporate not only unit economics but also documentation quality, regulatory alignment, and the ability to support training and consistent supply. In an environment where procedure efficiency and access route preferences are evolving, device selection should be revisited periodically to ensure alignment with updated clinical workflows.
The peripheral guidewire market is expanding on the strength of procedural demand, material innovation, and evolving access preferences, but the most consequential decisions will be made by organizations that can connect device performance to real workflow outcomes. Detailed segment-level sizing, regional demand patterns, and company-specific benchmarking will sharpen strategic planning and reveal where commercial leverage is greatest. For decision-makers seeking granular data and tailored recommendations, the full PW Consulting market research report provides deeper breakdowns and scenario-based guidance to support investment, portfolio, and procurement decisions under evolving clinical and regulatory conditions.
For detailed analysis of this topic, please visit the official page: Peripheral Guidewire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bearing Steel Market 2026: Why a 5.07% CAGR Early to 2032 Reflects Real Demand Shifts|Beyond the Numbers
By pmarketresearch, 2026-09-21
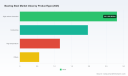
Strategic Trends and Commercial Opportunities in the Bearing Steel Market
The bearing steel market stands at a critical inflection point, shaped by the convergence of aerospace innovation, automotive electrification, and industrial automation. Over the historical period from 2020 to 2025, the market expanded from approximately $5.00 billion to $6.50 billion, reflecting steady demand acceleration across end-use sectors. Looking ahead through 2032, the trajectory points to a compound annual growth rate of 5.07 percent, with revenue projected to reach roughly $9.19 billion by the end of the forecast horizon. This growth pattern underscores a market that is not merely expanding in volume but is also undergoing structural transformation in material specifications, supply chain configuration, and regional balance.
Such a macro environment presents both opportunity and complexity. Demand is increasingly tied to performance-critical applications where bearing steel must withstand higher loads, elevated temperatures, and stricter cleanliness standards. Simultaneously, producers and end-users face volatility in raw material logistics, energy costs, and regulatory expectations around sustainability. Understanding how these forces interact is essential for executives evaluating capacity investments, procurement strategies, or product roadmaps.
Resilience Amid Raw Material and Energy Volatility
One of the most persistent challenges is the sensitivity of bearing steel production to energy prices, alloying element availability, and broader metallurgical input costs. The margin structure of specialty steel manufacturing depends heavily on controlled process conditions, scrap quality, and access to high-purity additives. When energy markets fluctuate or logistics networks tighten, producers must balance cost absorption with price pass-through, making margin stability a recurring concern. Companies that can decouple operating efficiency from commodity swings are better positioned to sustain profitability across cycles.
For downstream bearing manufacturers and OEMs, this volatility translates into longer planning horizons, more frequent contract renegotiations, and a stronger emphasis on supplier reliability. Procurement teams are increasingly prioritizing partners that can demonstrate consistent chemical control, traceability, and flexible delivery models. In practical terms, the cost challenge is less about absolute price levels and more about predictability and risk allocation across the value chain.
Performance Demands from Aerospace and Automotive Electrification
A second pivotal shift comes from the performance envelope required in next-generation applications. Aerospace engines and electric vehicle drivetrains are pushing bearing materials into higher temperature, higher load, and lower friction regimes. These applications demand not only superior fatigue strength and wear resistance but also compatibility with novel manufacturing approaches such as ceramic coatings, specialized heat treatments, and tighter cleanliness thresholds. The result is a market segment where incremental improvements in alloy design and process control can generate disproportionate value.
This trend creates a clear divergence between commodity-grade bearing steel and advanced, application-specific grades. As aerospace and automotive programs become more technology-intensive, the ability to certify and scale new steel formulations becomes a competitive differentiator. Firms that can align material development with the qualification timelines of OEMs gain access to higher-margin, longer-cycle relationships that are less susceptible to price competition.
Regional Rebalancing and Supply Chain Reconfiguration
A third structural factor is the ongoing rebalancing of regional production and demand patterns. Asia Pacific has emerged as a dominant demand center, reflecting the scale of automotive manufacturing, industrial equipment production, and infrastructure investment across the region. This concentration is reshaping supply chain logic, with regional sourcing priorities increasingly influenced by delivery reliability, trade policy, and the desire to reduce exposure to transoceanic disruptions.
At the same time, European and North American producers retain strengths in advanced metallurgical expertise, aerospace-grade certifications, and proximity to high-value end markets. The market is therefore not simply consolidating around one geography; instead, it is evolving into a multi-polar system where regional specialization, technology leadership, and logistics flexibility determine competitive advantage. Companies that can operate across this distributed landscape while maintaining quality consistency are gaining strategic leverage.
Advanced Alloy Development as a Core Growth Engine
Technological innovation remains the most direct driver of market value creation. Recent introductions of patented bearing steel alloys designed for higher load and temperature capacity illustrate how material science is opening new performance frontiers. These alloys are not merely incremental refinements; they enable tighter integration between bearing design and steel specification, allowing OEMs to optimize systems for weight reduction, efficiency, and durability.
The commercial implication is clear: advanced alloy development is shifting from a supporting function to a strategic capability. Producers that invest in proprietary grades, controlled melting practices, and application-specific testing can command premium positioning and longer-term customer engagement. This dynamic also raises the barrier to entry for commoditized producers, reinforcing a market structure in which differentiation increasingly depends on metallurgical know-how rather than scale alone.
Policy and Regulatory Pressures on Sustainability and Material Standards
Policy and regulatory evolution is shaping both production practices and demand behavior. Stricter expectations around carbon intensity, material traceability, and product lifecycle accountability are becoming embedded in procurement requirements across automotive, aerospace, and industrial sectors. These expectations are not abstract compliance issues; they influence supplier selection, product qualification, and long-term contract structures.
For bearing steel producers, the regulatory environment is accelerating investment in cleaner production methods, energy-efficient rolling and heat-treatment processes, and documentation systems that support transparent sourcing. The firms that treat sustainability as an operational capability rather than a reporting exercise are likely to secure stronger relationships with customers facing their own decarbonization targets. In this context, regulatory pressure functions as a catalyst for product and process innovation, not merely a constraint.
Demand-Side Shifts Across Automotive, Aerospace, and Industrial End-Use
On the demand side, the most influential change is the transformation of end-use requirements. Automotive applications continue to represent the largest share of market value, driven by both conventional drivetrain components and the evolving needs of electrified powertrains. Aerospace demand is intensifying as engine architectures become more demanding and as long-life, high-reliability components gain prominence. Industrial machinery and equipment add further support as automation, robotics, and high-cycle manufacturing expand.
This diversification matters because it alters the shape of demand growth. Rather than relying on a single dominant application, the market is increasingly supported by multiple specialty demand centers, each with different performance, certification, and volume characteristics. For producers and service providers, this means that portfolio breadth, application expertise, and the ability to customize steel grades are becoming more important than uniform volume growth.
Supply Chain Localization and Cost Structure Compression
Supply chain dynamics are also reshaping the cost structure and competitive logic of the bearing steel market. Regional sourcing preferences, inventory strategies, and risk mitigation priorities are encouraging closer alignment between steel producers and bearing manufacturers within key markets. This localization trend supports faster response times and greater transparency, but it also pressures producers to maintain cost efficiency at smaller regional scales.
At the same time, vertical integration is becoming more visible as an industry theme. Some bearing manufacturers maintain in-house steel production to secure consistency and reduce dependency on external suppliers, while others rely on specialized steelmakers with deep metallurgical capabilities. The interplay between integrated and specialized models is influencing pricing power, innovation cycles, and long-term resilience. Companies that can adapt their sourcing and production strategies to these evolving relationships are better equipped to manage both cost and performance risks.
Market Structure and Competitive Dynamics
The market remains moderately concentrated, with the top three players accounting for approximately 45 percent of share and the top five reaching roughly 55 percent. This structure reflects the advantages of scale, technical depth, and established customer relationships, but it also indicates room for differentiation through specialized products and regional leadership. Rather than a simple oligopoly, the landscape is characterized by overlapping strengths: some firms compete on aerospace-grade materials, others on high-cleanliness industrial grades, and others on integrated bearing solutions.
Sweden-based SKF illustrates the strategic importance of advanced alloy development with recent introductions of bearing steel formulations designed for next-generation aeroengine applications. Its focus on combining higher load capacity with elevated temperature tolerance highlights how material innovation can anchor high-value aerospace relationships. Sweden-based Ovako has reinforced a complementary position through bearing quality steel optimized for fatigue strength and high cleanliness, emphasizing consistent metallurgical control as a basis for serving major bearing manufacturers.
Japan-based producers are pursuing distinct pathways. Sanyo Special Steel continues to support aerospace and wind power applications by expanding high-cleanliness bearing steel grades, while Aichi Steel Corporation maintains a strong presence in high-carbon chrome bearing steel for automotive and industrial use. Nippon Steel contributes high-cleanliness grades within a broader specialty steel portfolio, and several Japanese bearing and engineering groups utilize in-house steel production to secure performance and supply reliability. NSK’s recent launch of ceramic-coated bearing steel balls for high-temperature aerospace applications underscores the trend toward hybrid material solutions, while JTEKT and NTN demonstrate the strategic value of integrating steel production with precision bearing manufacturing. Germany-based Saarstahl rounds out the competitive field with high-purity aluminum-free bearing steels targeting industrial and automotive applications.
Taken together, these profiles reveal a market in which differentiation is multi-dimensional. Some competitors compete on alloy novelty, others on cleanliness and fatigue performance, and others on vertical integration and application-specific product design. The presence of both steel specialists and bearing manufacturers with internal steel capabilities suggests a landscape where partnerships, co-development, and selective integration are all viable strategic models.
Evolution of the Competitive Landscape
The competitive dynamics are likely to become more layered rather than purely consolidated. On one hand, the technical complexity of advanced bearing steel supports continued advantages for established players with strong testing, certification, and production capabilities. On the other hand, demand for specialized grades and regional responsiveness creates openings for focused suppliers that can deliver high value in targeted segments. New entrants are unlikely to succeed through broad commodity positioning; instead, credible competition is emerging where firms can demonstrate clear performance advantages, reliable supply, or cost-efficient specialization.
High Carbon Bearing Steel Market
This evolution favors companies that can align their strategic positioning with the highest-value demand streams. Aerospace applications reward material innovation and qualification depth. Automotive applications reward scale, consistency, and cost discipline. Industrial applications reward flexibility and closeness to regional machine-building ecosystems. The firms that can articulate and execute a distinct value proposition within these streams are best placed to expand share without depending solely on volume-driven competition.
Trend One: Material Innovation as the Primary Value Frontier
Over the next three to five years, advanced material design is expected to remain the most important value frontier. As bearing systems face higher loads, greater thermal stress, and tighter efficiency requirements, the ability to offer steel grades that meet application-specific targets will increasingly determine commercial success. This trend benefits producers with strong internal R&D, application testing, and customer co-development capabilities. It also expands the opportunity set for hybrid solutions that combine steel with coatings or complementary materials, particularly in aerospace and high-performance industrial uses.
PW Consulting Health Care Research Center
The commercial opportunity lies not only in launching new grades but in building repeatable qualification pathways that reduce time-to-market for OEM programs. Companies that can shorten the loop between material development, validation, and production scale-up will capture a larger share of high-margin demand. The risk is that innovation cycles become expensive if not directed by clear end-use requirements, so disciplined portfolio targeting will matter as much as technical ambition.
Trend Two: Sustainability-Driven Procurement and Process Transformation
A second major trend is the deepening influence of sustainability criteria on procurement and production. Buyers are increasingly factoring carbon intensity, material traceability, and process transparency into supplier evaluations. This shift is encouraging investment in energy-efficient manufacturing, cleaner melting and refining practices, and documentation systems that support verifiable sourcing. The trend is especially relevant where automotive and aerospace customers operate under public decarbonization commitments and require supplier alignment.
Bearing for Steel Industry Market
For producers, the commercial implication is that sustainability can become a competitive parameter in its own right, not just a compliance requirement. Firms that can demonstrate credible progress and operationalize it across their product lines may gain preferential access to long-cycle contracts and co-development opportunities. The uncertainty lies in the pace and consistency of regulatory and customer requirements across regions, which can create uneven demand for “green” bearing steel until standards and expectations converge more fully.
Trend Three: Regional Specialization and Multi-Polar Supply Networks
The third trend is the continued regional specialization of demand and supply. Asia Pacific is expected to remain a substantial demand engine, while North America and Europe will likely sustain strength in advanced aerospace, industrial, and specialty automotive applications. This multi-polar structure encourages supply networks that are both regionally responsive and globally coordinated. Producers and bearing manufacturers that can manage this balance will be better positioned to reduce disruption risk while maintaining performance quality and delivery reliability.
The opportunity here is to design sourcing and production footprints that match the geography of high-value demand. For some companies, that means strengthening regional capacity or partnerships; for others, it means building flexible logistics and inventory strategies that support just-in-time performance without over-reliance on a single route. The risk is that regional fragmentation can raise duplication costs and complicate quality standardization, so the winners will be those who combine localized responsiveness with disciplined process control.
For Bearing Steel Producers and Material Developers
Producers should prioritize a focused portfolio strategy that distinguishes commodity continuity from advanced-grade growth. Commodity segments will remain essential for cash flow and scale, but value expansion is increasingly tied to specialty formulations, high cleanliness, and application-specific certification. It is strategically important to identify which end-use segments offer the best combination of performance premium, qualification feasibility, and volume potential, then align R&D and capacity decisions accordingly. Co-development with key bearing manufacturers and OEMs can shorten validation cycles and improve the likelihood that new grades translate into commercial adoption.
Operational resilience should also receive renewed attention. Energy efficiency, scrap and alloy management, and quality consistency are no longer just cost levers; they are strategic factors that influence customer trust and contract stability. Producers that can demonstrate both technical differentiation and dependable execution will be better positioned to maintain pricing power and expand into higher-value segments.
For Investors and Strategic Buyers
Investors should look beyond headline growth and assess where value is being created within the market. The most attractive exposure is likely in segments where advanced steel grades, certification depth, and application expertise translate into higher margins and stickier customer relationships. Vertical integration can be valuable when it secures quality and supply for high-performance bearings, but it is not universally superior; the optimal structure depends on whether a company’s advantage lies in steelmaking, bearing design, or both.
Valuation and due diligence should therefore focus on product mix, qualification pipelines, regional demand exposure, and the credibility of sustainability improvements. Companies with a clear link between material innovation and end-use performance are better positioned to capture the market’s projected growth trajectory. The main caution is that not all scale is equal: volume growth in undifferentiated segments may not generate proportional returns if pricing pressure and input volatility persist.
For Procurement and Engineering Leaders
Procurement and engineering leaders should treat bearing steel selection as a system-level decision rather than a standard commodity purchase. The performance requirements of aerospace, automotive electrification, and high-cycle industrial applications increasingly reward closer collaboration with suppliers on grade selection, cleanliness targets, and processing compatibility. Early engagement in the design and qualification phase can reduce downstream risk and improve total system efficiency, especially where new alloys or hybrid solutions are under consideration.
Supplier evaluation should incorporate not only price and delivery but also consistency of metallurgical control, traceability, and the ability to support evolving sustainability requirements. Diversifying the supplier base in a structured way can reduce exposure to regional disruptions while preserving access to advanced grades where needed. The key is to match sourcing strategy with application criticality: the more performance-sensitive the bearing system, the more important it is to secure partners with proven material expertise and reliable qualification support.
Why Timely Intelligence Matters Now
The bearing steel market is evolving quickly enough that decisions made on outdated assumptions can lock in suboptimal sourcing, product, or investment strategies. The combination of advanced alloy development, sustainability-driven procurement, and regional rebalancing means that competitive advantage is increasingly determined by how well companies understand shifting performance requirements and supply chain logic. Detailed segment-level data, application-specific demand patterns, and supplier capability assessments can make the difference between reactive adjustments and proactive positioning.
For organizations seeking a deeper view of these dynamics, the full PW Consulting research report provides more granular segmentation, regional breakdowns, and customized strategic recommendations tailored to specific business models and end-use exposures.
For detailed analysis of this topic, please visit the official page: Bearing Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
GET Market 2026: Why This 5.5% CAGR and $5.8B Outlook Changes Everything
By pmarketresearch, 2026-09-21
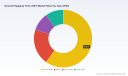
Strategic Shifts and Commercial Opportunities in the Global Ground Engaging Tools Market
The global market for ground engaging tools has entered a period of structural evolution. Valued at approximately USD 4,050 million in 2025, the market is projected to reach USD 5,800 million by 2032, representing a compound annual growth rate of 5.5% over the forecast period. Growth is not uniform across all geographies or equipment categories, but the overall trajectory reflects a maturing industry where performance optimization, total cost of ownership, and operational uptime increasingly drive purchasing decisions. The market remains moderately concentrated, with the top three players accounting for roughly 48.5% of revenue and the top five capturing about 65.2%. This concentration underscores scale advantages in engineering, distribution, and aftermarket service, while leaving meaningful room for specialized innovators and regional specialists to differentiate on fit, durability, and service responsiveness.
For executives and investors, the core question is not whether the market will grow, but how value will be created and captured as the industry transitions from replacement-driven demand to performance-driven procurement. The following analysis examines the defining challenges, demand and supply forces, competitive strategies, and forward-looking trends that will shape commercial outcomes through the end of the decade.
Market Landscape and Defining Pressures
The ground engaging tools market spans a broad portfolio of wear components—bucket teeth, adapters, blades, side cutters, lips, and complete bucket protection systems—deployed across excavators, loaders, dozers, and a range of other earthmoving and mining equipment. Bucket teeth represent the largest product category, reflecting their universal role across general construction and mining applications. Excavators anchor the application side of the market, followed by loaders and dozers, with the balance distributed across specialized attachments and mixed fleets. Regionally, North America and Europe together form the largest revenue base, while Asia Pacific and Latin America represent structurally faster-growing theaters tied to infrastructure development and mining expansion.
Several intersecting pressures are reshaping how manufacturers, fleet operators, and distributors approach the category:
- Material volatility and specification rigidity. Carbon steel wear plates, cutting edges, and high-abrasion steels remain foundational to ground engaging tools, yet they are subject to supply constraints and price fluctuations. At the same time, industry standards for hardox wear plate and high-abrasion steel continue to govern material selection, anchoring cost structures and requiring disciplined sourcing strategies.
- Skilled labor constraints are changing the value equation. Shortages of skilled technicians for heavy machinery maintenance are pushing operators toward long-life ground engaging tools and designs that reduce manual intervention. Components that resist premature wear, simplify replacement, and extend service intervals are gaining preference over lowest-unit-price alternatives.
- Safety standards are raising the bar on design. ISO and mining safety standards increasingly demand secure locking mechanisms in ground engaging tools, influencing product architecture and limiting the viability of indirect, non-conforming substitutes in regulated mining environments.
Together, these pressures are compressing price-based competition while elevating durability, interchangeability, and safety-compliant engineering as the primary arenas of differentiation. The strategic implication is clear: vendors that can stabilize input costs, design for serviceability, and align with recognized safety and material specifications will command stronger margin pools than those competing primarily on price.
What Is Driving Change: Technology, Regulation, Demand, and Supply
Technology and design innovation
Product innovation is shifting from incremental material improvements toward integrated systems that protect buckets, extend component life, and support faster replacement. Recent developments illustrate this direction. In April 2026, Bradken updated its ground engaging tools catalog with enhanced Zenith Plate Lip and Eclipse Cast Lip solutions, signaling continued emphasis on high-performance mining ground engaging tools for face shovels, front-end loaders, and backhoe excavators. In May 2026, Sandvik introduced the Mako™ GET as a next-generation bucket protection system tailored for underground loader operations, reinforcing the trend toward engineered protection packages that improve durability and productivity in demanding environments. Later in the same month, Haladjian Mining completed new ESCO® MaxDRP™ Ripper GET system installations for mining dozers, demonstrating how complete, specification-aligned systems are being deployed to optimize performance and equipment life in mining dozers and excavators.
Excavator Attachments Market
These releases share a common thread: they are not isolated wear parts but engineered systems designed to reduce operating costs and downtime. For manufacturers, the opportunity lies in bundling teeth, adapters, lips, and bucket protection into coherent configurations that simplify specification, improve fit, and reduce the risk of premature failure. For operators, this aligns with the broader industry shift toward monitored wear systems and digital monitoring technologies, which are accelerating adoption of data-informed maintenance decisions and creating a stronger link between component design and telemetry-compatible service models.
Policy and regulatory environment
Regulatory and standards-driven requirements are becoming a more decisive factor in product design and procurement. ISO and mining safety standards require secure locking mechanisms in ground engaging tools, which narrows the feasible design space and rewards manufacturers that can deliver compliant, field-proven solutions. Material specifications—particularly standards for hardox wear plate and high-abrasion steel—continue to shape what can be used in high-wear applications, reinforcing a preference for traceable, spec-aligned inputs in mining and regulated construction settings.
The commercial consequence is dual-edged. On one hand, compliance narrows the path for low-cost, non-conforming competitors and strengthens the moat for established engineering organizations. On the other hand, it imposes design and certification overhead that smaller entrants must manage carefully. Organizations that anticipate specification changes and invest in documented material traceability and locking-system integrity will find it easier to win and retain contracts in regulated segments.
Worldwide Ground Stabilization Geogrid Market
Demand-side behavior and fleet economics
Demand is being shaped less by headline equipment sales alone and more by how operators manage total cost of ownership. The decision to replace a tooth, adapter, or bucket protection system is increasingly evaluated against downtime, labor availability, and the durability of the installed configuration. In markets where skilled labor is scarce, long-life ground engaging tools and systems that reduce handling and installation time carry a premium. In mining, where machine utilization directly influences throughput, complete ground engaging systems that combine teeth, lips, adapters, and wear packages are gaining traction because they simplify specification and reduce variability in wear performance.
PW Consulting
In the aftermarket, the demand picture is broadening as fleets seek compatible wear parts that can be integrated across OEM and non-OEM equipment. A robust aftermarket ecosystem that offers teeth, adapters, cutting edges, blades, end-bits, and wear parts compatible with major manufacturer systems remains attractive to mixed-fleet operators who prioritize flexibility and uptime over single-brand lock-in. The practical insight for buyers is that compatibility, interchangeability, and documented performance across equipment types are becoming as important as the unit price of individual components.
Supply chain and cost structure dynamics
Cost structures are being pressured from both ends. On the input side, carbon steel wear plates and cutting edges are subject to supply constraints and price fluctuations, which can erode margins if not managed through specification discipline and supplier diversification. On the output side, competitive intensity among large, well-capitalized players and capable aftermarket specialists limits how much of those costs can be passed through in price-sensitive segments. The net effect is a strategic emphasis on design efficiency, material optimization, and service economies.
Manufacturers that can standardize high-performing configurations, reduce waste in fabrication, and align inventory with real wear patterns are better positioned to stabilize margins. At the same time, companies that can maintain regional service proximity and quick-turn availability for critical wear parts gain a measurable edge in markets where downtime is costly and logistics are complex.
Competitive Landscape and Strategic Positioning
The market’s moderate concentration reflects a layered competitive structure. Large, multi-brand manufacturers bring engineering scale, broad product lines, and integrated service networks. Specialized mining-focused producers compete on performance in demanding applications, often with differentiated lip, tooth, and wear-package designs. Aftermarket specialists provide broad compatibility and rapid local availability across major systems, enabling mixed-fleet operators to maintain uptime without full OEM dependence. The result is a market where scale, specialization, and service proximity each create distinct competitive advantages.
Several players illustrate how these advantages are being exercised:
- Caterpillar Inc. leverages a full line of ground engaging tools—including cutting edges, teeth, adapters, bucket protection, and Advansys systems—across excavators, wheel loaders, dozers, and mixed fleets. Its strategy emphasizes reducing operating costs and downtime, and recent moves such as extending Cat GET systems to support third-party buckets broaden the addressable market beyond proprietary equipment. This is a clear play to combine engineering credibility with fleet flexibility.
- ESCO Group LLC focuses on engineered lips, teeth, adapters, and full ground engaging systems for mining excavators, rope shovels, wheel loaders, and draglines. Its orientation toward optimizing performance and extending equipment life positions it strongly in mining applications where wear performance and system fit are closely scrutinized.
- Bradken Limited emphasizes high-performance mining ground engaging tools with differentiated solutions such as Zenith Plate Lip and Eclipse Cast Lip, along with bucket wear packages for face shovels, front-end loaders, and backhoe excavators. Its focus on demanding mining applications and periodic catalog refreshes illustrates a commitment to updating product architecture in line with field requirements.
- Sandvik AB provides the Shark™ GET range with Mako™ systems, Blue Pointer 2, profile bars, shrouds, and mechanical locking for underground mining buckets. The emphasis on durability, productivity, and mechanical locking aligns directly with safety and performance expectations in underground mining and demonstrates a systems-level approach to bucket protection.
- ITR America and ITR Africa operate extensive aftermarket lines of teeth, adapters, cutting edges, blades, end-bits, and wear parts compatible with major OEM systems for earthmoving equipment. Their value proposition centers on compatibility and availability across dozers, loaders, and excavators, which is especially relevant for mixed-fleet operators and regions with distributed service needs.
- Cutting Edge Supply offers a full range of aftermarket ground engaging tools—including cutting edges, teeth, adapters, buckets, and attachments—using alloy steels and hardox wear parts. This positions the company as a practical source for operators seeking spec-aligned materials and broad coverage in construction and earthmoving applications.
- Haladjian Mining provides the ESCO® MaxDRP™ Ripper GET systems, teeth, lips, and wear parts for mining dozers and excavators, supported by distributor-level installation activity. Its role highlights how regional execution and system-level offerings can deliver performance improvements in specific mining contexts.
Strategically, the market is evolving along three vectors. First, scale players are extending compatibility and service reach to capture value beyond proprietary equipment, as seen in moves to support third-party buckets with engineered ground engaging systems. Second, mining specialists are refining system designs and lip/teeth architectures to address high-wear conditions more effectively, often refreshing catalogs and product lines in response to field feedback. Third, aftermarket specialists continue to build regional density and compatibility breadth, making them indispensable to operators who manage diverse equipment pools. New entrants face the highest barriers where certification, material traceability, and locking-system integrity are required, but opportunities remain for focused innovators that can deliver differentiated wear performance, faster replacement, or telemetry-compatible service models.
Outlook Through 2032: Three Trends and What They Unlock
Looking ahead three to five years, the market direction is shaped by the convergence of material constraints, safety and specification requirements, and the growing importance of uptime economics. The following trends are likely to define commercial outcomes:
- From replacement parts to performance systems. Buyers will increasingly evaluate ground engaging tools as integrated protection and wear-management systems rather than collections of individual components. This favors manufacturers that can bundle teeth, adapters, lips, and bucket protection into coherent, documented configurations and provide guidance on specification and replacement intervals. Commercial opportunity lies in packaging, compatibility, and service-backed performance guarantees that reduce uncertainty for operators.
- Digital monitoring and data-informed wear management become mainstream. The accelerating adoption of monitored wear systems and digital monitoring technologies will link component design more tightly to usage data and maintenance planning. Over time, this creates opportunities for condition-based replacement, better inventory forecasting, and service offerings tied to actual wear rather than fixed schedules. The risk is that organizations without telemetry-compatible designs or data-driven service capabilities may lose share in fleets that prioritize predictive maintenance.
- Regional differentiation intensifies as cost and service pressures diverge. In price-sensitive segments, competition will remain tight, but in mining and regulated construction environments, durability, safety-compliant locking, and material traceability will command premiums. Regions with strong mining activity or infrastructure build-out will see faster demand growth for high-performance configurations, while mature markets will emphasize aftermarket breadth, component longevity, and mixed-fleet compatibility. Companies that localize service and inventory intelligently will capture more value than those relying on centralized, slow-turn models alone.
Potential risks and uncertainties should be monitored closely. Material price volatility and supply constraints can compress margins if input strategies are not diversified. Changes in safety and material standards can require redesigns and recertification, disproportionately affecting players with limited engineering bandwidth. Labor shortages can both increase demand for long-life tools and disrupt aftermarket execution if service capacity is insufficient. Finally, if monitored wear systems and digital tracking become widely adopted, data ownership and integration with fleet management platforms could emerge as new points of competitive differentiation, introducing vendor-lock-in considerations for operators.
Actionable Guidance for Decision-Makers
The commercial terrain is shifting from unit-price competition toward performance, compatibility, and service-driven value. Different roles in the value chain should respond accordingly.
For manufacturers and product leaders
- Design for system-level value. Prioritize configurations that combine teeth, adapters, lips, and bucket protection in documented packages that reduce specification complexity and downtime. Compatibility with major systems and support for third-party buckets can broaden addressable demand while preserving engineering credibility.
- Build resilience into the cost base. Diversify material sourcing for carbon steel wear plates and cutting edges, maintain spec-aligned documentation for hardox and high-abrasion steel usage, and standardize high-performing configurations to reduce fabrication waste and improve margin stability.
- Prepare for data-linked service. As monitored wear systems and digital monitoring technologies become more common, ensure component designs and service processes can integrate with usage data. This positions the product portfolio for condition-based maintenance offerings and more predictable aftermarket demand.
For investors and strategic planners
- Focus on durability economics. In a market where skilled labor is scarce and downtime is costly, long-life ground engaging tools and safety-compliant locking mechanisms have structural appeal. Evaluate exposure to regulated mining and infrastructure segments where performance and compliance can support stronger pricing power.
- Assess competitive moats by service proximity and compatibility breadth. Aftermarket specialists that combine spec-aligned materials with broad compatibility across OEM systems can sustain demand in mixed-fleet environments. Scale players with integrated service networks and expanding compatibility also warrant attention, especially where they can monetize uptime benefits beyond proprietary equipment.
- Watch for consolidation pressure in regional distribution. As product lines become more system-oriented and monitoring technologies mature, distribution models that can deliver fast-turn availability and technical support will gain importance. Gaps in regional service density may create both acquisition opportunities and execution risks.
For procurement, fleet managers, and contractors
- Specify for total cost of ownership, not just unit price. Evaluate ground engaging tools and systems against durability, replacement time, compatibility with existing equipment, and the reliability of locking mechanisms. In labor-constrained environments, designs that are durable and easy to service can reduce hidden costs that are often larger than the component price itself.
- Standardize where it pays. For mixed fleets, prioritize wear parts and systems with proven compatibility across major manufacturer configurations to simplify stocking, reduce errors, and keep equipment running. Documented performance and safety-compliant designs should be weighted alongside cost when making specification decisions.
- Plan inventory around real wear patterns. As monitored wear systems become more widespread, align stocking and replacement planning with actual usage data rather than fixed intervals. This reduces both stockouts and overstock, especially for high-wear applications in mining and heavy construction.
The most consequential decisions in this market will be made by organizations that can translate material constraints, safety requirements, and uptime economics into coherent product, sourcing, and service strategies. For readers seeking a more detailed segmentation view, regional demand pathways, and tailored recommendations for specific equipment categories and growth markets, the full PW Consulting study on the Ground Engaging Tools market provides deeper sub-segment data and customized guidance to support planning with precision.
For detailed analysis of this topic, please visit the official page: Ground Engaging Tools (GET) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
MMOEXP bietet eine der zuverlässigsten Lösungen für den Kauf von Spielwährungen, Gegenständen, Accounts und vielem mehr. Jetzt können Sie den exklusiven Rabattcode „east“ nutzen, um sich einen Rabatt von 8 % zu sichern.
Der Launch-Scale-Test von Aion 2 hat vielen Spielern einen ersten umfassenden Eindruck vom kommenden MMORPG ermöglicht. Besonders interessant waren dabei das Kampfsystem, die neue Welt und der allgemeine Spielfluss. Auch die Bedeutung von Aion 2 Kinah wurde bereits während des Tests deutlich, da die Ingame-Währung für verschiedene Aktivitäten und die Charakterentwicklung eine wichtige Rolle spielt. Doch kann Aion 2 tatsächlich die Erwartungen der MMORPG-Community erfüllen?
Eine Große Welt Mit Vielen Möglichkeiten
Aion 2 setzt auf eine deutlich größere Spielwelt als der ursprüngliche Titel. Die Welt von Atreia wurde erweitert und bietet zahlreiche Gebiete, Quests und Aktivitäten. Dadurch entsteht bereits während der ersten Spielstunden das Gefühl, dass Spieler langfristig viel zu entdecken haben.
Besonders auffällig ist die moderne technische Präsentation. Die Umgebung wirkt detaillierter und lebendiger, während Charaktermodelle und Effekte einen zeitgemäßen Eindruck vermitteln. Gleichzeitig versucht Aion 2, bekannte Elemente der Serie mit neuen Spielmechaniken zu verbinden.
Kampfsystem Und Charakterentwicklung
Ein wichtiger Bestandteil des Scale-Tests war das Kampfsystem. Fähigkeiten müssen gezielt eingesetzt werden, während Positionierung und Reaktionsvermögen je nach Situation eine größere Rolle spielen können. Dadurch fühlen sich Kämpfe aktiver an als bei manchen klassischen MMORPGs.
Auch die Charakterentwicklung bietet zahlreiche Möglichkeiten. Ausrüstung, Fähigkeiten und verschiedene Verbesserungen ermöglichen es Spielern, ihre Figuren an den eigenen Spielstil anzupassen. Dafür werden im späteren Spielverlauf natürlich auch Ressourcen benötigt, weshalb Aion 2 Kinah einen wichtigen Bestandteil der Wirtschaft darstellt.
Dungeons Und Gruppeninhalte
Aion 2 richtet sich nicht ausschließlich an Einzelspieler. Dungeons und andere Gruppenaktivitäten bilden einen wichtigen Teil des Spielerlebnisses. Wer gemeinsam mit Freunden spielt, kann verschiedene Klassen miteinander kombinieren und dadurch anspruchsvollere Gegner bewältigen.
Gerade diese Gruppeninhalte könnten langfristig entscheidend dafür sein, wie abwechslungsreich das Endgame ausfällt. Der Scale-Test konnte hier bereits einen ersten Eindruck vermitteln, allerdings wird das vollständige Angebot erst zum offiziellen Start sichtbar werden.
Wie Wichtig Ist Aion 2 Kinah?
Die Ingame-Währung dürfte für die langfristige Entwicklung eines Charakters eine zentrale Rolle spielen. Spieler benötigen Ressourcen unter anderem für Ausrüstung, Handwerk und verschiedene Fortschritte. Wer seine verfügbaren Ressourcen sinnvoll einsetzt, kann seine Entwicklung effizienter gestalten.
Spieler, die ihre Wirtschaft im Spiel besser organisieren möchten, können sich außerdem auf der Handelsplattform von MMOExp über verfügbare Optionen informieren. Mit dem Rabattcode „east“ erhalten Kunden dort einen Nachlass von 8 %.
Lohnt Sich Aion 2?
Der Launch-Scale-Test vermittelt insgesamt einen interessanten ersten Eindruck. Die große Spielwelt, das modernisierte Kampfsystem und die verschiedenen Gruppeninhalte bieten eine solide Grundlage für ein langfristiges MMORPG. Gleichzeitig bleiben einige Fragen offen, insbesondere hinsichtlich Endgame, Balancing und der langfristigen Wirtschaft.
Wer Aion 2 zum Start spielen möchte, sollte sich deshalb frühzeitig mit Ausrüstung, Charakterentwicklung und der Nutzung von Aion 2 Kinah beschäftigen. Für Spieler, die zusätzliche Ressourcen benötigen, kann es sich lohnen, auf der MMOExp-Handelsplattform nach passenden Angeboten zu schauen und beim Aion 2 Kinah kaufen den Rabattcode „east“ für 8 % Rabatt zu nutzen.
Rubber Sheet Market 2026: Decoding the True Drivers Behind 4.4% CAGR Growth
By pmarketresearch, 2026-09-21
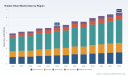
Strategic Trends and Commercial Opportunities in the Rubber Sheet Market
The global rubber sheet market has entered a phase of steady, investment-grade expansion. Fueled by consistent demand across industrial, automotive, and specialty manufacturing sectors, the market has scaled from 3.94 billion USD in 2020 to an estimated 4.89 billion USD in 2025. Forward-looking projections indicate the market will reach 6.64 billion USD by 2032, underpinned by a compound annual growth rate of 4.4 percent between 2026 and 2032. This trajectory reflects more than cyclical recovery; it signals a structural recalibration driven by material innovation, evolving regulatory frameworks, and shifting end-user expectations. For executives navigating procurement, production, or capital allocation, understanding the forces reshaping this arena is no longer optional.
Market Size, Growth Trajectory, and Structural Positioning
The revenue expansion observed over the past five years has been relatively uniform, though the composition behind the headline figures reveals important nuances. The market is not growing through a single vertical or geography but through a combination of mature industrial demand, emerging applications in healthcare and clean energy, and deliberate premiumization in material specifications. Asia Pacific continues to account for the largest revenue share, reflecting both manufacturing density and infrastructure build-out, while North America and Europe maintain strong positions anchored in automotive, chemical processing, and regulated industrial environments. Growth is not purely volume-driven; higher-margin specialty grades and performance-enhanced synthetics are gradually capturing a larger slice of total revenue, indicating a market that is incrementally shifting from commodity substitution toward value-engineered solutions.
Beneath the steady growth curve lies a competitive structure that remains moderately fragmented at the top but increasingly polarized in capability. The top three participants collectively command roughly 35 percent of market revenue, while the top five reach approximately 50 percent. This concentration suggests that scale, technical service, and supply chain reliability still differentiate winners, but it also leaves meaningful room for regional specialists, custom fabricators, and technology-focused entrants to compete on specification intensity rather than sheer volume. The market is not consolidating into a handful of dominant players; rather, it is stratifying into tiers where leadership is defined by material expertise, certification readiness, and the ability to translate application requirements into repeatable production processes.
Key Challenges and Inflection Points
Despite the constructive growth outlook, the industry is navigating several pressure points that are reshaping competitive dynamics and margin structures.
-
Raw material volatility and sourcing complexity. Natural rubber pricing has experienced sharp movements recently, with futures trading above 230 US cents per kilogram in early June 2026, marking the highest level since January 2017. In India, official data from June 2026 recorded RSS1 at INR 30,462 per 100 kilograms and RSS4 at INR 26,500 per 100 kilograms. These price signals reflect supply constraints and geographic imbalances that ripple through formulation decisions, inventory planning, and pricing strategies across the value chain. For sheet producers and converters, this volatility is not a transient issue; it is becoming a structural cost-management challenge that demands more sophisticated hedging, blending, and specification triage.
-
Regulatory traceability and compliance burdens. The EU Deforestation Regulation has moved from policy concept to operational reality, requiring plot-level traceability and auditable sourcing for natural rubber entering premium export channels. This requirement is reshaping who can access high-value European markets, forcing supply chains to document origin, verify land-use practices, and build audit-ready systems. While the regulation primarily targets deforestation-linked commodities, its practical effect on the rubber sheet sector is significant: it raises the barrier to entry for premium natural rubber grades, accelerates the shift toward certified or synthetic alternatives, and rewards suppliers with transparent, digitally traceable sourcing infrastructure.
-
Performance versus cost tension in end-use applications. Automotive, chemical processing, mining, pharmaceutical, and healthcare buyers increasingly demand sheets that meet stricter mechanical, chemical, and environmental criteria without a proportional increase in cost. Meeting these expectations requires more than incremental grade improvements; it calls for formulation innovation, tighter process control, and often a willingness to invest in application-specific validation. Companies that treat specification requirements as a compliance checkbox rather than a value-creation opportunity risk losing share to competitors who can demonstrate measurable performance gains, lower lifecycle cost, or faster qualification cycles.
Core Drivers Reshaping the Market
The growth and differentiation underway in the rubber sheet market are not accidental. They are being pulled by several reinforcing forces that are altering where value is created and how companies compete.
Technological Innovation and Material Breakthroughs
Material science is steadily expanding the boundary of what rubber sheets can deliver in demanding environments. Formulation advances are enabling better resistance to oils, solvents, temperature extremes, and abrasion while maintaining flexibility and ease of fabrication. Equally important, the push toward sustainability is becoming a technology driver rather than a compliance burden. Recent industry moves illustrate this shift clearly: in September 2024, ContiTech introduced a new line of eco-friendly rubber sheets incorporating bio-based fillers designed to reduce carbon footprint. That same direction continued into 2025, when Envire Flooring launched Envire® Rubber Sheet & Tile with VOC emissions compliant with CA Section 01350 and FloorScore/GreenGuard Gold certification. These developments are not isolated product launches; they signal a broader transition in which environmental performance, indoor air quality, and carbon-intensity reduction are becoming specification criteria alongside traditional mechanical properties.
For manufacturers, this means innovation is increasingly multi-dimensional. Success depends on the ability to combine performance attributes with sustainability credentials, certification readiness, and consistent batch-to-batch quality. Suppliers that can deliver these combinations in repeatable production environments are gaining leverage in negotiations, particularly with buyers facing their own scope 3 targets or procurement mandates tied to low-emission materials.
Ribbed Smoked Sheet Rubber Rss Market
Policy and Regulatory Environment
Policy is moving from a background constraint to a front-line strategic variable. Environmental and sourcing regulations are compelling buyers and suppliers to treat traceability, emissions, and material provenance as core purchasing criteria. The EU Deforestation Regulation's plot-level traceability and auditable sourcing requirements are already influencing premium export channel access for natural rubber. While the regulatory burden is real, it also creates a sorting mechanism: suppliers with robust documentation, verified sourcing, and transparent chain-of-custody systems are better positioned to maintain or expand access to high-value markets, while those without such infrastructure face mounting commercial friction.
Beyond environmental rules, broader industrial safety and chemical management standards continue to shape specification choices. In regulated sectors such as pharmaceuticals, healthcare, and certain chemical processing environments, certification and emissions compliance increasingly determine which products can be considered at all. Regulatory momentum therefore has a dual effect: it compresses the addressable market for non-compliant offerings while expanding the premium for suppliers that can demonstrate credible compliance and test-ready documentation.
Rubber Flooring Market
Demand-Side Shifts in Buyer Behavior
Purchasing behavior is evolving from transactional price comparison toward total cost and risk evaluation. Automotive OEMs and tier suppliers, chemical manufacturers, mining operators, and healthcare and pharma buyers are increasingly weighing factors such as material consistency, certification status, supplier technical support, and lifecycle durability alongside unit price. This shift is particularly pronounced where sheet rubber is integrated into safety-critical, regulated, or high-uptime applications, because failure or variability carries consequences that far outweigh marginal cost differences.
At the same time, demand is diversifying. Automotive remains the largest application segment by revenue, reflecting continuing needs in sealing, vibration damping, gasketing, and component fabrication. Chemicals and mining applications contribute substantial volume, driven by containment, abrasion resistance, and harsh-environment performance. Meanwhile, pharmaceutical and healthcare use is expanding as hygiene, cleanliness, and low-emission requirements become more stringent. The result is a market in which demand is not only growing but also fragmenting into more specification-intensive pockets, each with distinct performance and compliance expectations.
Supply Chain and Cost Structure Evolution
Cost structures are being reshaped by raw material dynamics, energy considerations, logistics complexity, and the premium attached to reliability. The recent surge in natural rubber futures and the elevated domestic price levels observed in key producing regions underscore how quickly input costs can move when supply tightness coincides with steady demand. For sheet producers, the implication is clear: cost management is no longer a matter of negotiating a single resin or latex price. It requires portfolio-level decisions about natural versus synthetic blending, grade selection aligned to application needs, inventory buffering strategies, and the use of alternative fillers or reinforcements where performance permits.
Supply chain resilience is becoming a competitive asset in its own right. Buyers are increasingly sensitive to lead-time stability, minimum order flexibility, technical responsiveness, and the ability to support custom or specialty configurations. This favors companies that have invested in integrated production capabilities, predictable quality systems, and the operational discipline to handle both high-volume standard grades and lower-volume specialty orders without sacrificing service levels. In a market where top-five players already command about half of total revenue, differentiated service and supply reliability can be as decisive as product attributes when contracts are awarded.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of regional manufacturers, custom fabricators, specialty material suppliers, and global industrial players. Each cluster approaches the market with a distinct value proposition, and the most successful firms are aligning their capabilities with the segments where they can win on specification and reliability rather than competing broadly on price alone.
WARCO, based in Orange, California, has built its position around a broad natural and synthetic sheet portfolio, including nitrile, EPDM, neoprene, silicone, HNBR, Viton, and custom spec-grade rubber for industrial and specialty uses. This breadth allows the company to serve buyers who require multiple elastomer types under a single sourcing relationship, simplifying procurement while maintaining the ability to match material properties to application demands. Aero Rubber Company in Tinley Park, Illinois, competes on volume and customization, producing custom molded, extruded, and fabricated rubber components alongside custom sheets and slabs. Its strength lies in integrated fabrication capability, which can reduce downstream processing burden for customers that prefer a more complete component solution rather than bare sheet material.
Hanna Rubber Company focuses on calendered sheet rubber in extra-thick, super-thin, or double-wide options, including custom and specialty fabrics. This positioning targets buyers who need dimensional flexibility and fabric integration for specific manufacturing or installation requirements. American Biltrite, operating across Canada and the United States, emphasizes premium-quality sheet rubber across major elastomers in various gauges, widths, and sizes with fabric reinforcement, appealing to customers that prioritize consistent gauge control and reinforced performance. BRP Manufacturing in Lima, Ohio, serves military, automotive, aerospace, and industrial customers with high-quality sheet rubber and extruded rubber products, a mix that demands rigorous specification control and the ability to meet demanding end-use standards.
International players add further diversity. TOGAWA Rubber in Japan produces rubber sheets for industrial gaskets, floor mats, and extrusion applications, reflecting a focus on precision and application-specific patterning. Zenith Rubber in Mumbai, India, has manufactured rubber sheets, mats, flooring, and industrial rubber products since 1965, leveraging long experience and regional cost advantages while serving both domestic and export demand. Rubberteck International in Busan, South Korea, supplies anti-static and other rubber sheets for industrial applications, highlighting a niche where electrostatic control and specialized performance justify dedicated sourcing. ContiTech, a division of Continental based in Germany, produces high-performance rubber sheets and materials for industrial applications, combining global scale with engineering credibility and, increasingly, sustainability-forward product development.
What ties these leaders together is not identical product lines but strategic clarity. The strongest players are differentiating along one or more of the following axes: material breadth and spec-grade customization, integrated fabrication and component capability, dimensional and fabric-reinforcement specialization, sector-specific certification and compliance readiness, and sustainability-driven formulation. This is a market where generalists can survive, but specialists and clearly positioned players tend to capture more defensible margins.
Evolution of the Competitive Landscape
The market is not heading toward outright consolidation into a few dominant firms. Instead, it is evolving through capability layering and segmentation. Larger, multi-elastomer producers are expanding their technical service and sustainability portfolios to protect share in regulated and premium segments. Custom fabricators and molded-component manufacturers are gaining relevance as buyers seek to offload more processing steps and reduce integration risk. Regional specialists continue to compete effectively where local service, cost structure, and application knowledge matter more than global scale. Meanwhile, new entrants and niche players are finding openings in anti-static, low-emission, and bio-based or certified material segments where specification intensity creates room for focused offerings.
A practical implication is that competitive advantage is increasingly defined by the ability to operate across multiple value dimensions at once: consistent quality, traceable sourcing, certification readiness, technical support, and sustainable formulation options. Companies that only compete on volume or price are more exposed to raw material swings and regulatory sorting, while those that combine material expertise with service depth and compliance credibility are better positioned to defend margins and win specification decisions.
Future Trends and Commercial Opportunities
Looking ahead over the next three to five years, several trends are likely to shape where growth concentrates and how value is captured.
-
Sustainability performance becomes a default specification dimension. Low-emission products, bio-based fillers, and certified or traceable sourcing will move from differentiators to baseline expectations in a growing share of applications, particularly in Europe, North America, and regulated industrial sectors. Commercial opportunity lies with manufacturers that can offer credible, test-backed sustainability claims without sacrificing mechanical or chemical performance, and with procurement teams that can integrate these criteria into sourcing scorecards before specifications become locked in by competitors.
-
Premium natural rubber channels become more selective and compliance-dependent. As traceability and audit requirements reshape access to high-value export markets, suppliers with robust documentation and verified sourcing will enjoy preferential access, while others face narrowing options. This creates opportunity for companies that invest early in chain-of-custody systems, supplier documentation, and digital traceability, as well as for buyers that secure reliable, compliant supply ahead of broader market tightening.
-
Customization and application-specific engineering gain share over generic commodity sheets. Demand is increasingly oriented toward specific gauges, fabric reinforcements, anti-static properties, chemical resistance profiles, and low-VOC formulations. The opportunity is not simply to sell more sheet by weight but to sell solutions that reduce downstream processing, accelerate qualification, lower failure risk, and support total-cost objectives. For producers, this means building flexible production and technical-service capabilities; for investors, it means evaluating whether target companies can sustain premium positioning through engineering value rather than volume alone.
These trends carry risk as well as opportunity. Raw material volatility can compress margins if pricing power and formulation flexibility are limited. Regulatory requirements may raise compliance costs and exclude suppliers that cannot meet traceability or emissions thresholds. Demand-side expectations can shift faster than production capabilities, leaving slower-responding firms with mismatched inventories or obsolete grade mixes. The upside, however, belongs to organizations that treat these pressures as planning inputs and respond with deliberate investment in material capability, compliance infrastructure, and specification-level differentiation.
PW Consulting Chemical & Energy Research Center
Actionable Guidance for Decision Makers
For manufacturers, the priority is to sharpen the link between material portfolio, application expertise, and compliance readiness. This means reviewing whether product lines map clearly to the highest-value segments, whether formulation flexibility allows intelligent blending or grade substitution in response to raw material movement, and whether sustainability and traceability capabilities are sufficiently developed to meet rising specification requirements. Companies should also assess whether their fabrication, custom-spec, or technical-service capabilities are strong enough to win on total solution value rather than competing only on sheet price.
For investors, the focus should be on structural positioning rather than headline growth alone. Evaluate whether target companies have defensible differentiation through material breadth, specialty grades, certification readiness, or integrated fabrication; whether their cost and sourcing strategies can withstand raw material volatility; and whether their sustainability roadmap is grounded in product reality and test-backed claims rather than marketing language. Preference should go to operators that can demonstrate a repeatable ability to win specification decisions in regulated or performance-critical segments, because those decisions tend to be stickier and more margin-protective over time.
For procurement and supply chain leaders, the strategic task is to broaden evaluation criteria beyond unit cost and to secure supply clarity ahead of regulatory and price pressures. Incorporate traceability, emissions compliance, batch consistency, technical support, and lifecycle performance into sourcing frameworks. Where natural rubber exposure is significant, consider supply diversification, certified or compliant channel planning, and formulation strategies that preserve performance while managing input risk. Early engagement with suppliers that already meet emerging traceability and low-emission expectations can reduce qualification delays and protect continuity in premium channels.
The market's direction is clear enough to warrant action, but the details that determine competitive success are highly segment-specific. Trim-level specification mixes, regional sourcing constraints, certification requirements, and application-level performance thresholds vary widely, and generic assumptions often lead to mispriced risk or missed openings. Decision makers who need granular segment data, company-level capability mapping, and tailored scenario analysis will find greater value in structured, deeper research than in broad market narratives. For those evaluating strategic moves, gathering detailed intelligence on segment growth drivers, competitive positioning, regulatory exposure, and material-cost sensitivity is a practical next step before committing capital, renegotiating supply, or redesigning product roadmaps.
For detailed analysis of this topic, please visit the official page: Rubber Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Digital Remittance Market 2026: Why 15.8% CAGR Growth Changes Everything
By pmarketresearch, 2026-09-21
The Digital Remittance Market: Strategic Trends and Commercial Opportunities in a Rapidly Evolving Landscape
Market Overview and Core Challenges
The digital remittance market has transitioned from a niche convenience to a fundamental infrastructure layer for global money movement. Between 2020 and 2025, the sector expanded from approximately $8.7 billion to nearly $24.9 billion, reflecting a compound annual growth rate of 15.8% over the period. Looking ahead to 2032, trajectory modeling suggests the market will reach roughly $69.4 billion, sustained by the same structural forces that accelerated adoption over the past half-decade. Growth is not uniform across all segments, but the overall expansion signals a durable shift away from cash-dependent, branch-heavy transfer models toward digital, mobile-first, and increasingly automated channels.
Despite the headline momentum, the industry sits at a critical inflection point. Three interconnected challenges define the current environment. First, regulatory fragmentation continues to raise the cost of cross-border compliance, particularly for providers operating across multiple jurisdictions with divergent anti-money laundering and consumer protection standards. Second, the economics of last-mile delivery remain strained, especially in markets where telecommunications infrastructure costs, spectrum licensing, and agent network maintenance compress margins. Third, customer expectations have reset the competitive baseline: speed, transparency, and low friction are no longer differentiators; they are table stakes, which puts pressure on incumbent cost structures and forces continuous reinvestment in technology and partnerships.
These pressures are not purely defensive. They are reshaping who can compete, how value is captured, and where the next wave of margin improvement will originate. For decision-makers, the practical question is not whether digital remittance will keep growing, but which structural shifts will determine winners and laggards over the next several years.
Key Drivers of Market Change
Technological Innovation and Platform Integration
Technology is compressing the distance between origination and receipt while simultaneously lowering the marginal cost of each transfer. Mobile applications, messaging-based interfaces, and wallet integrations are extending reach into contexts where traditional banking penetration is limited but smartphone and data connectivity are expanding rapidly. Real-time payment rails, programmable settlement, and API-first infrastructure are enabling providers to embed remittance capabilities into broader financial and commercial workflows rather than treating them as standalone transactions.
The shift toward messaging and conversational interfaces illustrates how product design is expanding access. Recent product launches have shown providers using familiar communication platforms to reduce friction for both senders and recipients, including features that allow recipients to initiate requests directly and expansions of message-based sending into additional countries. In parallel, stablecoin-based settlement experiments are being used to test faster, more predictable cross-border movement of value, particularly where traditional correspondent banking routes are slow or expensive. These developments do not replace the need for strong compliance and liquidity management, but they do change the operating model by moving more of the transaction lifecycle into digital, traceable, and automatable workflows.
Policy and Regulatory Environment
Regulation remains one of the most powerful levers shaping market structure, cost, and speed. In the United States, new federal excise tax provisions on certain remittance transfers funded by cash, money orders, or cashier's checks have introduced a differentiated cost environment, with digitally funded transfers using bank or card sources exempt from the tax. Proposed regulatory clarifications around the scope of remittance transfer taxation further signal that policymakers are actively defining which channels and funding methods fall under new obligations. For operators, this creates both a pricing dynamic and a strategic incentive to steer customers toward digital funding paths that are more efficient from a tax and compliance standpoint.
At the same time, international regulatory bodies have been tightening expectations around risk-based oversight for digital channels. Guidance emphasizing AML/CFT compliance for digital remittance providers reflects a broader push to ensure that faster, more automated channels do not weaken oversight. Complementary analysis from multilateral forums has highlighted persistent licensing and regulatory barriers that can slow digitization, particularly for non-bank providers seeking to operate across borders. The net effect is a market where compliance capability is becoming a competitive asset rather than a back-office function. Providers that can align product design, onboarding, monitoring, and reporting with evolving requirements are better positioned to scale without running into structural bottlenecks.
Shifts in Consumer and Business Behavior
Demand-side behavior is changing on two tracks. For personal users, the expectation is increasingly about seamless, low-cost, and trackable transfers that fit into daily digital routines. Senders want clarity on fees and exchange rates, while recipients often prefer immediate availability through local wallets, bank accounts, or cash pickup where digital liquidity is not yet universal. This dual expectation pushes providers to offer multiple payout options and to optimize for local relevance rather than a single global template.
On the business side, cross-border payments are becoming more embedded in operational workflows. Companies that source, pay, or employ across jurisdictions need predictable settlement, multi-currency management, and automation that reduces manual intervention. This has increased interest in infrastructure-oriented solutions that connect enterprises to local payout networks and provide FX and payment capabilities in a more integrated form. As a result, the market is not only expanding in volume but also broadening in use cases, with business-driven flows becoming a meaningful component of overall digital remittance activity.
Cost Structure and Infrastructure Dynamics
The cost side of the market is being redefined by both technology and local infrastructure conditions. Digital channels can reduce some legacy handling costs, but they do not eliminate the expense of maintaining liquidity, managing FX exposure, meeting compliance requirements, and delivering reliable last-mile payouts. In some regions, telecommunications and spectrum-related costs add measurable pressure to the operating environment, affecting the economics of mobile-based delivery and agent-supported networks. Where infrastructure costs are elevated, providers must either absorb them, pass them through carefully, or redesign distribution to reduce dependence on high-cost pathways.
This creates an opportunity for differentiation based on distribution efficiency. Providers that can combine digital onboarding with optimized payout routing, selective partnerships, and stronger working capital management can improve unit economics even in challenging local conditions. Conversely, operators that rely on high-cost legacy touchpoints without sufficient automation may find margin expansion difficult, especially as customers compare experiences across increasingly transparent pricing environments.
Competitive Landscape and Leading Strategies
The competitive field blends established global transfer brands, technology-native platforms, and infrastructure-focused providers. Each group is pursuing a different angle of value creation, and the landscape is evolving through a mix of expansion, consolidation, and targeted partnership activity.
Several leading players have built their positioning around transparency, speed, and channel convenience. Some emphasize predictable exchange rates and low-cost bank-funded transfers, appealing to users who prioritize clarity and efficiency. Others leverage extensive agent and pickup networks alongside digital channels, preserving cash-oriented access while modernizing the front end. A third cohort focuses on platform and messaging integration, using familiar consumer touchpoints to expand reach and reduce onboarding friction. These divergent approaches reflect different assumptions about where the biggest growth and retention leverage lies: price transparency, physical reachability, or digital convenience.
A separate but increasingly important set of players operates more as enabling infrastructure than as consumer-facing brands. These providers supply cross-border payment and remittance capabilities to fintechs, banks, and enterprises, often emphasizing real-time settlement, multi-currency accounts, and localized payout capabilities. Their growth illustrates a broader trend: as more entities seek to embed international money movement into their own products or operations, the demand for robust backend rails and compliance-ready integrations is rising.
PW Consulting
Recent activity shows how companies are trying to extend their advantage. One global provider expanded a messaging-based sending feature into additional markets and introduced a recipient-initiated request capability, reinforcing a strategy centered on reducing friction and increasing engagement through familiar communication channels. Another major player introduced a stablecoin tied to its remittance network, signaling an interest in using digital asset infrastructure to support faster settlement and network expansion. A separate cross-border platform secured a partnership to enable transfers directly into a major regional wallet and linked bank accounts, highlighting the continued importance of local payment system access in high-volume markets.
Digital Insurance Market
Taken together, these moves point to a market that is both consolidating around strong digital brands and fragmenting through specialized infrastructure plays. Incumbents are modernizing distribution and experimenting with new settlement models, while newer and mid-sized players are carving out niches based on enterprise needs, regional payout strength, or integration depth. The likely trajectory over the next few years is not a single dominant model, but a layered ecosystem in which consumer-facing brands, B2B infrastructure providers, and local access partners compete and cooperate simultaneously.
Future Trends and Commercial Opportunities
Deeper Integration of Messaging, Wallets, and Embedded Flows
Over the next three to five years, digital remittance is likely to become less visible as a standalone product and more embedded into everyday digital interactions. Messaging-based requests, wallet-to-wallet movement, and integration with broader financial apps will continue to reduce the steps between intent and completion. For commercial players, this creates opportunities to design products that are not just about moving money, but about supporting the surrounding workflows: bill payment, family support, supplier settlement, and payroll-related cross-border needs. The winners will be those that can make the transfer experience feel local, immediate, and contextually relevant rather than generic and transactional.
Regulatory Capability as a Competitive Moat
As tax rules, licensing expectations, and compliance guidance continue to evolve, regulatory competence will increasingly separate scalable operators from those that face repeated friction. Providers that invest early in compliant digital onboarding, transaction monitoring, and transparent funding-path design will be better placed to manage cost exposure and expand into new corridors. There is also an opportunity for providers that can help customers navigate differentiated tax and funding environments by steering them toward more efficient digital channels, provided this is done with clear communication and strong compliance foundations. In practical terms, regulatory readiness will become part of the product value proposition, not just a legal requirement.
Stable Settlement Innovation and Corridor-Specific Optimization
Experiments with stablecoin-based settlement and other digital asset infrastructure are likely to mature in select corridors where speed, FX certainty, and liquidity management matter most. This does not imply uniform adoption across all markets; instead, it suggests a corridor-by-corridor optimization dynamic. Where traditional rails are slower or more expensive, digital settlement layers may offer meaningful improvements, especially when paired with strong local payout partners and robust risk controls. The commercial opportunity lies in identifying which corridors benefit most from alternative settlement, building reliable liquidity and compliance support around them, and integrating these capabilities without disrupting the customer experience.
These trends carry risks. Regulatory changes can shift cost structures quickly, especially where tax treatment or licensing rules differentiate between funding methods or provider types. Infrastructure costs in certain regions can constrain distribution economics, making it harder to scale without a tailored model. FX volatility, liquidity management, and fraud or misuse risks remain persistent challenges in any high-volume cross-border environment. Finally, customer adoption can be uneven: digital convenience expands reach, but not every recipient market is ready for fully digital payout, which means hybrid models will remain necessary for years.
Strategic Recommendations for Decision-Makers
For executives, investors, and operators evaluating the digital remittance space, the most useful lens is to treat the market as a set of shifting cost, compliance, and distribution dynamics rather than as a simple volume growth story. The following actions can help translate that perspective into better decisions.
Digital Banking Market
- Align product and funding-path design with the changing cost and tax environment. Where digital bank- or card-funded transfers carry different implications than cash-based funding, optimize the experience to make the more efficient path attractive and easy to use, while maintaining clear customer communication and compliance integrity.
- Invest in compliance and operational scalability as core product capabilities. Strong onboarding, monitoring, reporting, and licensing readiness should be treated as enablers of expansion, especially for providers planning to enter new corridors or serve business customers with higher documentation and control expectations.
- Build corridor-specific distribution strategies instead of relying on a single global template. Local payout preferences, wallet penetration, agent networks, and infrastructure costs vary widely. Tailoring routing, partnerships, and payout options to local conditions can improve unit economics and customer satisfaction more reliably than standardizing every market.
- Evaluate infrastructure and partnership plays for enterprise and embedded use cases. As more businesses and platforms seek integrated cross-border payment capabilities, there is room to capture value by providing reliable rails, multi-currency management, and localized settlement support, particularly when paired with strong FX and automation features.
- Monitor settlement innovation selectively and operationally. Where alternative settlement models can improve speed or cost in specific corridors, test them with disciplined risk controls and liquidity management. Avoid broad commitments until the corridor economics, regulatory stance, and customer readiness are well understood.
The strategic value of detailed intelligence in this market is high because the differences between corridors, funding paths, compliance regimes, and distribution models can decisively affect profitability and scalability. Broad market narratives are useful for orientation, but operational decisions depend on finer-grained insight into where growth is concentrated, which channels are most efficient, how regulatory changes alter cost structures, and which partnership or infrastructure models fit a given business profile. For leaders who need that level of clarity, a full research report can provide the segmented data, corridor-level context, and customized strategic guidance necessary to move from directional confidence to executable planning.
For detailed analysis of this topic, please visit the official page: Digital Remittance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Real Drivers Behind the Epoxy Resin Active Toughening Agent Market 6.4% CAGR Link Up to 2032
By pmarketresearch, 2026-09-21
Active Toughening Agents for Epoxy Resins: Strategic Shifts and Commercial Opportunities Through 2032
Market Overview and Critical Inflection Points
The global market for active toughening agents designed for epoxy resin systems has entered a phase of deliberate, structurally driven growth. Valued at 81.25 million USD in 2025, the market has expanded from 60.0 million USD in 2020, reflecting a compound annual growth rate of approximately 6.4 percent across the 2026 to 2032 forecast horizon. This trajectory is not defined by cyclical commodity swings, but by a steady recalibration of how epoxy formulations balance rigidity, thermal stability, and fracture resistance across demanding industrial and high-performance applications. As design engineers push composite laminates, structural adhesives, protective coatings, and electronic encapsulants into more severe service environments, the traditional compromise between mechanical toughness and baseline performance is being systematically redefined by chemistry, processing economics, and end-use requirements.
The market’s evolution carries a clear concentration profile. The top three participants capture roughly 55 percent of global revenue, while the leading five firms account for nearly 68 percent. This distribution signals a mature competitive arena where scale, intellectual property depth, and formulation expertise create meaningful barriers to entry. At the same time, it leaves sufficient fragmentation for specialized regional players and application-focused innovators to carve out defensible positions. Rather than a winner-take-all contest, the landscape favors organizations that can translate material science into consistent processing windows, application-specific performance, and supply reliability.
The Core Tensions Reshaping the Sector
Three interconnected challenges are redefining how manufacturers, formulators, and end-users approach epoxy toughening. The first is the persistent performance-efficiency paradox. Historically, introducing rubber or thermoplastic reinforcement into epoxy networks has improved impact resistance and crack tolerance, but often at the expense of viscosity control, glass transition temperature, or thermal stability. Bridging that gap increasingly demands nanoscale dispersion control, reactive compatibility strategies, and self-assembling architectures that deliver toughness without degrading the host matrix’s baseline characteristics.
The second tension stems from regulatory and sustainability acceleration. Industrial flooring, protective coatings, construction applications, and marine asset maintenance are moving toward formulations that reduce volatile organic compound exposure, lower lifecycle carbon intensity, and improve compatibility with circular-economy expectations. In parallel, downstream industries are asking for more transparent sourcing, lower toxicity footprints, and formulations that simplify end-of-life handling or enable higher recycled-content integration. Meeting these requirements without sacrificing mechanical reliability or shelf stability forces formulation teams to re-evaluate incumbent chemistries and evaluate bio-based, low-emission, or hybrid toughening strategies.
The third inflection point is the shifting center of gravity in demand intensity. Growth is no longer distributed evenly across legacy applications. Semiconductor packaging, battery enclosures, lightweight structural assemblies, and high-durability offshore and marine systems are placing disproportionate emphasis on materials that can withstand thermal cycling, vibration, moisture exposure, and mechanical fatigue while supporting weight reduction and extended maintenance intervals. This demand migration changes the economics of product design, because performance tolerances tighten and qualification cycles lengthen, which in turn raises the value of specialized toughening solutions relative to broad-line commodity additives.
For business leaders, these tensions translate into a straightforward but demanding strategic question: whether to compete on cost-and-volume scale, on differentiated performance architecture, or on application-specific formulation partnerships. The answer increasingly depends on how well an organization can anticipate end-use qualification requirements and manage the trade-offs between toughness, processability, and regulatory alignment.
Key Drivers of Market Change
Material Innovation and the Rise of Precision Toughening
The most consequential driver of market momentum is the shift from blunt toughening tactics to precision-engineered reinforcement architectures. Traditional rubber-modified and thermoplastic toughening approaches remain relevant, but they are increasingly complemented by pre-dispersed concentrates, nano-scale core-shell particles, reactive block copolymers, and hyper-branched structures that integrate more cleanly into epoxy networks. These architectures can improve fracture toughness, fatigue resistance, and damage tolerance while preserving heat resistance, rigidity, and thermal properties that high-performance applications require. In structural adhesives, composites, and electronics, that balance is not a luxury feature; it is often the difference between a viable solution and one that fails qualification testing under thermal shock, impact, or long-term load.
One practical indicator of this shift is the commercial emphasis on pre-dispersed concentrate systems that simplify handling and dispersion for epoxy formulators. Nano-sized core-shell rubber particles incorporated into liquid media, for example, reduce particle agglomeration risk and lower the burden on downstream processing, while offering enhancements in impact strength, adhesive performance, and heat shock resistance. Such systems illustrate why the toughening conversation is moving away from generic additive categories and toward engineered intermediates that solve real process and performance pain points. For epoxy processors, this means faster reformulation support, better repeatability, and a cleaner translation from lab-scale performance to production-scale reliability.
Regulatory and Sustainability Pressure as a Catalyst, Not Just a Constraint
Policy and regulatory dynamics are accelerating change rather than merely restricting it. In European construction and industrial coating contexts, tighter sustainability expectations are pushing formulators toward low-VOC and bio-based formulations that meet both performance and environmental criteria. Far from being a compliance tax, this evolution is spawning a new class of requirement-led innovation: bio-based toughening agents, low-emission epoxy systems, and formulations designed for industrial flooring and protective coatings that must satisfy durability standards while reducing environmental burden.
The commercial implication is that sustainability is becoming a design input at the start of product development rather than a retrofit target. Companies that can supply toughening agents and epoxy-compatible chemistries with credible sustainability attributes may gain access to higher-value programs where procurement teams must justify material choices across lifecycle, regulatory, and reputational dimensions. Conversely, formulations that lag on VOC profile, bio-based content, or transparency of supply may face growing friction in markets where specification approvals are subject to stricter evaluation.
Demand-Side Transformation in High-Performance End-Use Sectors
On the demand side, the most meaningful shift is the increasing need for epoxy systems that survive more demanding service conditions while supporting lighter, more efficient designs. In semiconductor and battery packaging contexts, lightweight composite requirements and tighter tolerance bands are driving higher interest in tailored toughening solutions that protect sensitive assemblies from stress, thermal mismatch, and cyclic loading. Similarly, in offshore and marine asset maintenance, epoxy coatings are being specified not only for protection but for extended maintenance intervals, which raises the premium on mechanical durability and chemical resistance under prolonged exposure.
These demand signals matter because they change the basis of competition. Applications that tolerate marginal performance can absorb cost-led substitution; applications where failure carries high operational, safety, or capital consequences do not. As a result, toughening agents are increasingly evaluated through the lens of end-use reliability, qualification support, and compatibility with specific processing routes. Formulators and end-users alike are pushing for materials that reduce risk in the field, which gives a structural advantage to suppliers that can document performance under realistic conditions rather than rely solely on generic benchmark data.
Supply Chain, Cost Structure, and Formulation Economics
The cost and supply side adds another layer of complexity. Toughening agents are rarely purchased as isolated commodities; they are integrated into broader formulation strategies where dispersion quality, shelf stability, viscosity control, and batch consistency influence total cost of ownership. When regulatory shifts, feedstock transitions, or regional sourcing constraints alter input economics, the impact is magnified because downstream processors must balance performance targets with manufacturability and cost predictability. At the same time, the move toward pre-dispersed and pre-engineered systems can reduce formulation complexity in production, potentially lowering labor, dispersion equipment burden, and process variability even if the per-unit material cost is higher.
Epoxy Active Diluent Market
This dynamic favors companies that can offer not just chemistry, but process-aligned solutions. For epoxy processors, the value proposition increasingly includes dispersibility, compatibility with target resin systems, and the ability to maintain performance without unacceptable trade-offs in modulus or glass transition behavior. In practical terms, that means supplier selection is becoming less about price-per-kilogram alone and more about whether the toughening agent helps the end formulation meet target properties within a stable, scalable process window.
Competitive Landscape and Leading Strategies
Differentiation Through Formulation Architecture and Application Focus
The market’s competitive frontier is defined less by sheer volume and more by how companies translate material science into application-specific advantage. Global specialty chemical players tend to emphasize high-performance architectures, proprietary toughening chemistries, and integration with advanced composite or adhesive systems. Their strategic positioning often centers on solving demanding end-use problems where toughness must coexist with elevated thermal performance, damage tolerance, or very tight mechanical specifications. For example, self-assembling block copolymer-based toughening systems and thermoplastic polyester sulfone micropowders are being positioned where epoxy composites and prepregs need improved toughness and damage resistance without sacrificing key structural properties.
These approaches create differentiation through performance architecture rather than price alone. When a toughening solution can demonstrably improve damage tolerance or toughness while maintaining modulus and glass transition behavior, it becomes easier to defend in specifications that are sensitive to both mechanical reliability and thermal stability. That is especially relevant in automotive structural adhesives, CFRP-related aerospace applications, and other settings where heat resistance, rigidity, and impact tolerance must all remain within acceptable bounds.
PW Consulting Chemical & Energy Research Center
Regional Strengths, Specialization, and Scale
Alongside global specialists, a broad set of regional and application-focused manufacturers contributes meaningful scale and breadth across rubber, thermoplastic, core-shell latex, hyper-branched, and reactive toughening variants. These players often compete by covering multiple application domains, maintaining responsive production and customization capabilities, and aligning product portfolios to coatings, adhesives, composites, and certain electronics uses. Their advantage frequently lies in breadth, localization, and the ability to serve customers who need a practical range of toughening options rather than a single high-end architecture.
Worldwide Epoxy Resin Curing Agents Market
The strategic relevance of this fragmentation should not be underestimated. In many industrial and regional markets, buyers prioritize availability, formulation flexibility, and cost-sensitive performance tuning over the most advanced but narrowly focused specialty option. That creates durable roles for suppliers that can balance product range with consistent quality and practical technical support. At the same time, the most specialized applications reward deep technical differentiation, which means competitive advantage is increasingly bifurcated: breadth for broad industrial demand, and performance depth for mission-critical applications.
Market Evolution: Consolidation Pressure and Entry Opportunities
Looking ahead, the competitive structure is likely to evolve through a mix of consolidation pressure and selective entry opportunities. The concentrated top tier suggests that scale, IP portfolios, and integrated application development provide meaningful defensive moats. Yet the fragmentation below the top tier indicates room for companies that can build defensible niches through application expertise, regional supply strength, or differentiated toughening chemistry.
Entry and expansion opportunities are particularly likely in areas where performance requirements are rising faster than incumbent portfolios can adapt cleanly: bio-based and low-emission toughening, pre-dispersed concentrate systems for easier processing, and specialized solutions for electronics and composite packaging where lightweighting and reliability converge. At the same time, consolidation pressures may intensify among mid-tier players seeking to expand application coverage, improve scale economics, or acquire technical capabilities that strengthen their position with specification-driven buyers. The market is thus moving toward a structure where the winners are those who can combine credible performance claims with process-compatible delivery and clear application alignment.
Forward Outlook: Three Strategic Trends to 2032
Trend One: Toughening as an Engineered System, Not a Commodity Additive
Over the next three to five years, active toughening agents are likely to be treated more like engineered formulation systems than generic performance additives. That means greater emphasis on dispersion control, reactive compatibility, rheology management, and the ability to preserve modulus and thermal properties while improving toughness and damage resistance. Buyers will increasingly evaluate toughening agents on the basis of total formulation impact rather than isolated mechanical metrics. The commercial opportunity lies in solutions that reduce reformulation friction, improve repeatability, and help epoxy systems meet demanding targets without requiring extensive process re-engineering.
Trend Two: Sustainability-Linked Performance Becomes a Specification Requirement
Sustainability-driven formulation requirements are expected to become more embedded in procurement and specification processes, especially in coatings, industrial flooring, protective systems, and construction-adjacent applications. Low-VOC profiles, bio-based content, and lifecycle considerations will increasingly influence which toughening chemistries are eligible for consideration. This trend does not simply reward “greener” products; it rewards products that can demonstrate credible performance under the same demanding conditions as conventional alternatives. The opportunity is for suppliers and formulators who can pair sustainability attributes with robust mechanical and durability performance, turning environmental compliance into a competitive entry point rather than a constraint.
Trend Three: High-Reliability Applications Drive Higher-Value Demand
A third trend is the continued rise of high-reliability applications where failure is expensive and specifications are tight. Semiconductor and battery packaging, lightweight structural assemblies, and durable marine or offshore coatings are expected to place disproportionate emphasis on toughness, thermal cycling resistance, and extended service life. In these settings, the value of a toughening agent is tied to its ability to reduce risk and support qualification, not merely to improve a single performance parameter. The commercial opportunity lies in capturing demand from applications that are willing to pay for reliability, consistency, and technical support, while managing the risk that qualification timelines and technical barriers can slow adoption.
These trends together suggest a market that is growing at a measured but meaningful pace, with the strongest value creation concentrated where performance, process compatibility, and sustainability converge. The upside is real, but so is the risk that over-indexing on any single dimension—cost, performance, or sustainability—without the others can limit commercial viability in specification-driven environments.
Strategic Actions for Decision-Makers
For Epoxy Manufacturers and Formulators
Evaluate toughening agents as part of a total formulation strategy rather than as interchangeable additives. Prioritize solutions that align with your processing constraints, target viscosity and modulus profiles, and end-use qualification requirements. Where sustainability or low-emission performance is becoming a purchasing requirement, treat it as a design input early, and validate that any bio-based or low-VOC toughening approach can still meet mechanical and durability benchmarks in the intended application.
For Investors and Corporate Development Teams
Focus on the intersection of application-driven demand and differentiated chemistry. The most resilient opportunities are likely to be in specialized toughening architectures that address concrete performance problems in composites, structural adhesives, protective coatings, and high-reliability electronics or battery-related uses. Monitor consolidation dynamics among mid-tier players, and assess whether a target’s advantage comes from genuine technical differentiation, application relationships, or regional scale. Where demand is concentrated in high-specification applications, valuation logic should reflect qualification barriers and technical moats, not just volume growth.
For Procurement and Specification Teams
Build sourcing decisions around total cost of ownership, application reliability, and supplier capability to support qualification and formulation tuning. Request performance data that reflects the conditions under which the epoxy system will actually operate, including thermal cycling, impact, adhesion, and long-term durability where relevant. In markets where regulatory and sustainability expectations are tightening, verify that the selected toughening approach supports compliance without undermining field performance, because specification risk in demanding applications can far outweigh modest initial material savings.
For teams seeking a more granular view of segmentation, regional dynamics, competitive positioning, and forward scenarios across coatings, adhesives, composites, electronics, and high-performance industrial applications, a deeper dive into detailed market data and tailored strategic analysis can sharpen planning assumptions and reduce the risk of poorly aligned decisions. The broader opportunity in the active toughening agent space for epoxy resins is clear, but the details—where value concentrates, which applications justify premium performance, and how sustainability requirements will reshape specifications—will determine which companies capture it and which merely watch it pass.
For detailed analysis of this topic, please visit the official page: Active Toughening Agent for Epoxy Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com